Short Term Loan for a Security Deposit on a New Rental
A short term loan for a security deposit on a new rental can cover upfront move-in costs fast. See how to compare offers and avoid expensive mistakes.
By Ethan Davis
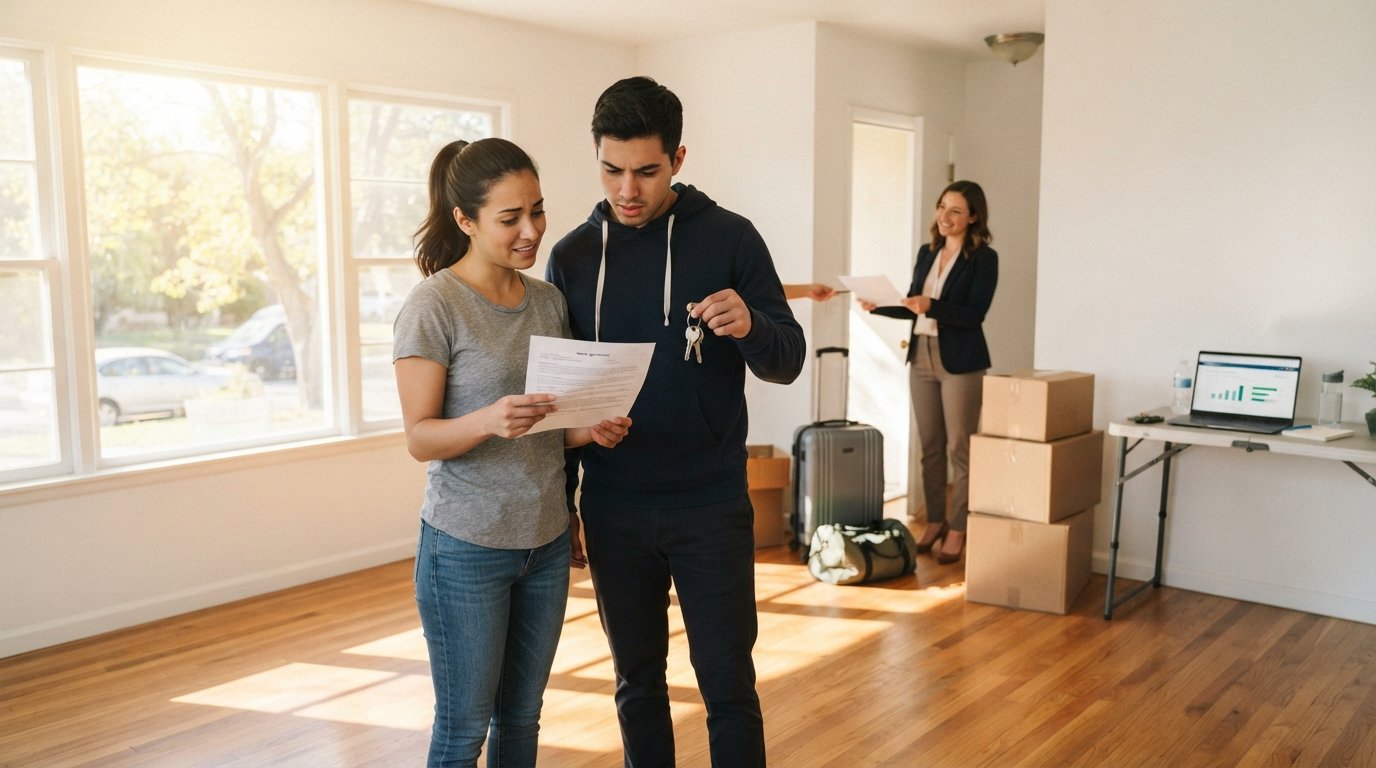
Finding the right apartment often comes down to timing, and timing usually comes down to money. You have toured the units, picked your favorite, and filled out the application. Then the leasing agent hands you the number: first month's rent plus a security deposit, all due before you get the keys. For many renters, that lump sum arrives at the worst possible moment, especially if you are already covering moving costs, utility hookups, and the deposit on your current place. A short term loan for a security deposit on a new rental can bridge that gap so you do not lose the unit to another applicant with cash in hand.
This guide walks through how security deposit loans work, what they realistically cost, when they make sense, and how to apply through a platform like ExpressCash that matches your request with a network of independent lenders. You will also learn the alternatives worth comparing before you sign anything, plus the mistakes that turn a manageable deposit gap into a long-term financial problem.
Why Security Deposits Create a Cash Flow Crunch
A security deposit is not rent. It is money your landlord holds to cover potential damage, unpaid rent, or lease violations after you move out. In most markets, that deposit equals one month's rent, though some landlords ask for more if you have limited rental history or a weaker credit profile. When you add application fees, a broker fee in certain cities, and the cost of actually moving your belongings, the total upfront number can easily reach two or three times your monthly rent.
The timing problem is what makes this so painful. Deposits are due at lease signing, but your current landlord may not return your old deposit until weeks after you vacate. That creates a gap where you are technically owed money but cannot access it yet. Paycheck timing compounds the issue. If you get paid on the first and fifteenth, a mid-month lease start can leave you short even when your overall budget is fine.
Renters in expensive metro areas feel this most acutely. A one-bedroom in a major city might rent for $1,800, which means a $1,800 deposit plus $1,800 first month's rent, plus moving costs. That is nearly $4,000 before you have unpacked a single box. For households without a fully funded emergency savings account, a short term loan for a security deposit on a new rental becomes a practical tool rather than a luxury.
How a Short Term Loan for a Security Deposit Works
A short term loan is a small-dollar loan designed to be repaid quickly, typically over a few weeks to a few months. When you take one out for a rental deposit, you are borrowing the deposit amount and agreeing to repay it with interest and any applicable fees according to a set schedule. The lender does not care what the money is for, so you can use the funds for the deposit, first month's rent, moving truck, or any combination of upfront costs.
Most short term loans for rental deposits fall into one of a few categories. Payday loans are the shortest and smallest, usually due on your next payday. Installment loans split repayment into multiple scheduled payments, which makes the total cost more predictable. Personal loans from online lenders can offer larger amounts and longer terms, though approval standards vary. A cash advance through a lending network works similarly to a payday loan but may come from a different type of provider.
The application process is almost entirely online. You submit basic personal, employment, and banking information, and the platform routes your request to lenders who may be willing to make an offer. If you are approved, funds are typically deposited directly into your bank account, often as soon as the next business day. You then repay according to the terms you accepted, either through automatic debits or manual payments.
One important distinction: the platform you apply through is usually not the lender. ExpressCash, for example, is a connection service that matches your request with third-party lenders. The lender sets the rates, fees, and repayment terms, and you are free to decline any offer that does not work for you. That no-obligation structure matters because it lets you compare offers without committing.
What a Rental Deposit Loan Actually Costs
Cost is where short term loans get complicated, and where borrowers need to pay close attention. The sticker price of a loan is not just the interest rate. It is the total of all finance charges, origination fees, and any late or returned payment fees. A loan that looks cheap on a per-day basis can become expensive if you roll it over or extend it repeatedly.
Payday loans are the most expensive category. A typical payday loan might charge $15 to $30 per $100 borrowed, which translates to an annual percentage rate in the triple digits. Installment loans and personal loans usually carry lower APRs, but they spread payments over a longer period, so you may pay more total interest even at a lower rate. The right comparison is not just the APR; it is the total dollar cost of borrowing versus the cost of not getting the apartment.
Here is a simple framework for evaluating whether a rental deposit loan is worth it:
- Total repayment amount: Add up every payment you will make and compare it to the amount borrowed.
- Repayment timeline: Confirm exactly when each payment is due and whether it aligns with your pay schedule.
- Prepayment terms: Check whether you can pay off early without a penalty, which reduces total cost.
- Consequences of default: Understand late fees, collection practices, and whether the lender reports to credit bureaus.
- Alternative costs: Compare the loan cost to losing the apartment, paying a higher rent elsewhere, or delaying your move.
Run those numbers before you accept an offer. If the total cost of the loan is less than the value of securing the apartment, and you can comfortably repay it on schedule, the math may work. If repayment would strain your budget for months, a different approach is probably better.
For a broader look at how these products fit into a larger borrowing strategy, our guide on short term funding for urgent needs explains how different loan types compare when you are facing a deadline.
When a Short Term Loan for a Security Deposit Makes Sense
Short term loans are not ideal for every situation, but there are scenarios where they are clearly the better option. The strongest case is when you have a confirmed income stream that will cover repayment within the loan term, and the only problem is timing. If you are starting a new job in two weeks, or your old deposit is scheduled to be returned next month, a short term loan can smooth that gap without derailing your finances.
Another reasonable scenario is when the apartment you are considering is significantly cheaper or better located than your alternatives, and losing it would cost you more in the long run. Paying $150 in loan fees to secure a unit that saves you $200 per month is a straightforward trade. The key is that the loan solves a temporary problem and does not become a recurring crutch.
On the other hand, there are situations where a short term loan for a security deposit on a new rental is a bad idea. If you are already behind on bills, if your income is unstable, or if you would need to roll the loan over to repay it, the risk of a debt spiral is high. In those cases, negotiating with the landlord, finding a cosigner, or choosing a less expensive unit is usually the smarter move.
It also helps to think about what happens after the move. A deposit loan adds a new monthly payment on top of your rent, utilities, and other obligations. If your post-move budget is already tight, that extra payment can push you into overdraft or missed bill territory. Run a realistic post-move budget before you borrow, not after.
How to Apply Through a Lending Connection Service
Applying through a connection service like ExpressCash is designed to be fast and low-friction. The process typically takes less than five minutes, and you can complete it from your phone or computer. Here is what to expect:
- Submit your information: Provide basic details such as your name, address, income, and bank account information. The form is encrypted with 256-bit SSL security.
- Get matched with lenders: Your request is routed to lenders in the network who may be willing to make an offer based on your profile.
- Review your offers: If you receive an offer, read the terms carefully, including the APR, fees, and repayment schedule.
- Accept or decline: You are under no obligation to accept any offer. If the terms do not work, you can walk away.
- Receive funds: If you accept, funds may be deposited as soon as the next business day, depending on your bank and the lender.
Because ExpressCash is not a direct lender, it does not make credit decisions or set loan terms. That means the rates and offers you see will vary based on the lenders in the network and your individual financial profile. Borrowers with bad credit may still receive offers, though the terms may be less favorable than what someone with excellent credit would see.
Before you apply, gather your documents. You will typically need proof of income, a valid ID, and an active bank account. Having those ready speeds up the process and reduces the chance of a delay that could cost you the apartment. You can also visit 4Payday to explore additional short-term borrowing options if you want to compare multiple sources before committing.
Alternatives to a Security Deposit Loan
Before you borrow, it is worth checking whether a less expensive option is available. A short term loan for a security deposit on a new rental is one tool, but it is not the only one. Sometimes a quick conversation with your landlord or a small adjustment to your plan can eliminate the need to borrow entirely.
Here are the most common alternatives and how they compare:
- Negotiate a payment plan: Some landlords will accept the deposit in installments if you ask before signing. This costs nothing and keeps you out of debt.
- Use a deposit alternative program: Companies like Rhino or Jetty charge a small monthly fee instead of a full deposit. You pay less upfront but do not get the money back.
- Ask for a cosigner: A cosigner with strong credit or income may reduce or eliminate the deposit requirement.
- Borrow from family or friends: A short-term personal loan from someone you trust is usually the cheapest option if it is available.
- Use a credit card: If you have available credit, a card may be cheaper than a payday loan, though carrying a balance can get expensive fast.
Each option has trade-offs. Deposit alternatives are convenient but non-refundable. Cosigners help you qualify but put someone else on the hook. Credit cards are flexible but can lead to revolving debt if you do not pay the balance quickly. Compare the total cost of each path before deciding.
How to Protect Yourself When Borrowing for a Deposit
Short term lending is a regulated industry, but not all lenders operate the same way. Protecting yourself starts with knowing your rights and reading every document before you sign. Federal and state laws govern disclosure requirements, fee limits, and collection practices, and legitimate lenders follow those rules.
Watch for red flags. A lender that pressures you to sign immediately, refuses to disclose fees in writing, or asks for unusual payment methods like gift cards is almost certainly not legitimate. You should also verify that the lender is licensed in your state, since loan availability and terms vary by location. ExpressCash and similar platforms typically state clearly that they are connection services, not lenders, and that loan terms are set by the third-party lenders in their network.
Responsible borrowing also means borrowing only what you need. If the deposit is $1,200, do not borrow $2,000 just because you qualify. Every extra dollar adds interest and increases the risk of missing a payment. Set up automatic payments if you can, and pay off the loan as early as your terms allow to reduce total cost.
Building a Plan to Avoid Future Deposit Gaps
Once the move is done and the loan is repaid, the goal is to avoid needing another short term loan the next time you relocate. That starts with building a dedicated moving fund. Even setting aside $50 per paycheck can create a cushion over a year. Treat it as a non-negotiable expense, like rent or insurance.
It also helps to understand how your credit profile affects your options. A stronger credit score can unlock lower rates on personal loans and may even help you negotiate with landlords. Paying bills on time, keeping credit card balances low, and checking your credit report for errors are all steps that improve your standing over time.
Finally, remember that a short term loan for a security deposit on a new rental is a bridge, not a foundation. Used carefully, it solves a timing problem and gets you into a home you can afford. Used carelessly, it creates a new financial obligation that follows you long after the move. The difference comes down to planning, reading the terms, and borrowing only when the numbers genuinely work.