Pet Emergency Vet Bill: How to Pay Fast in 2026
Facing a pet emergency vet bill you cannot pay upfront? Compare fast options like short-term loans, payment plans, and credit cards to get treatment now.
By Hannah Adler
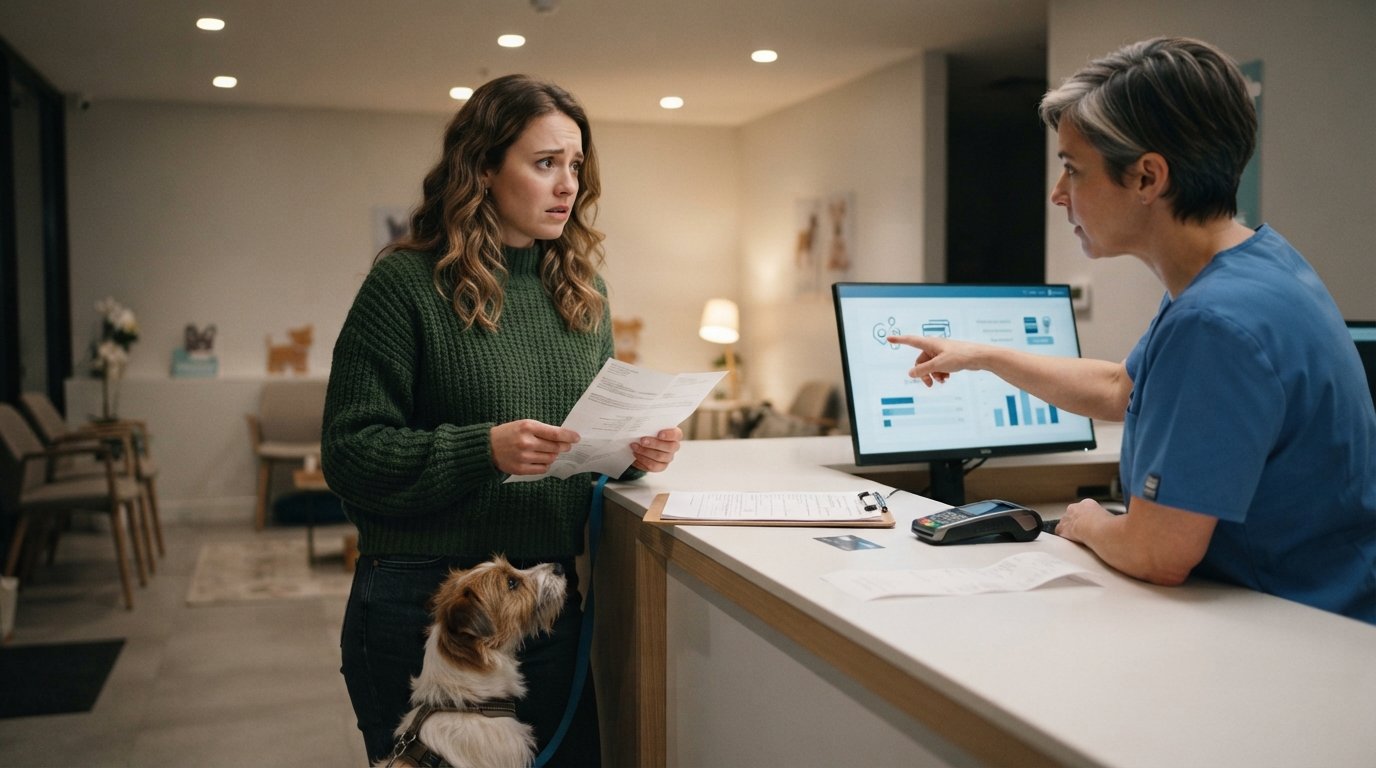
Your dog swallows a sock at 10 p.m. Your cat stops eating and hides under the bed. The emergency clinic quotes $2,400 before they even start treatment. You have $300 in checking and a credit card that is already close to its limit. This is the moment when a pet emergency vet bill how to pay fast question stops being theoretical and becomes a race against time. The good news is that you have more options than you think, and some of them can be activated while you are standing at the front desk. The key is knowing which ones work immediately, which ones require paperwork, and which ones might cost you far more than the bill itself.
Ask the Vet These Questions Before You Agree to Treatment
Before you swipe a card or sign a financing agreement, slow down for two minutes and ask the clinic a few direct questions. Emergency veterinary practices deal with financial stress every day, and most have protocols in place that they will not mention unless you ask. The first question is whether the estimate includes everything or just the initial stabilization. Many quotes cover diagnostics, IV fluids, and pain management, but then a second estimate appears after the X-rays come back. Ask for a written high-end and low-end estimate so you can see the full range before committing.
The second question is whether the clinic offers an in-house payment plan. Some corporate-owned emergency hospitals partner with third-party financing companies that offer six to twelve months of no-interest payments if you qualify. Others offer a simple promissory note with a deposit. You will never know unless you ask the front desk directly. The third question is whether you can pay a deposit now and the balance when you pick up your pet. Many clinics will accept 50 percent upfront and the rest at discharge, which buys you 24 to 48 hours to arrange funding.
Here are the specific questions to ask before treatment begins, in order of priority:
- What is the total estimated cost, including diagnostics, treatment, and aftercare?
- Do you offer an in-house payment plan or a deposit-plus-balance arrangement?
- Which third-party financing partners do you work with, and can I apply at the front desk?
- Can you provide a written estimate with a low-end and high-end range?
- Is there a discount for paying the full amount upfront or for using a specific payment method?
Once you have answers, you can make a clear-eyed decision. A clinic that will not budge on full payment upfront is not necessarily unreasonable, but a clinic that will work with you is far more common than most pet owners expect. The conversation itself costs nothing and can save you hundreds of dollars in rushed decisions.
Short-Term Loans and Personal Loans: Fast Cash for the Front Desk
When savings are not enough and the clinic needs payment now, a short-term loan or personal loan is often the fastest realistic option. The application process for an online loan can take less than five minutes, and if you are approved by a lender in the network, funds may be available as soon as the next business day. That timeline matters because many emergency clinics will hold a treatment plan for 24 hours while you arrange financing. You fill out a free, no-obligation request, get matched with independent lenders, and review the terms before you accept anything.
It helps to understand what you are applying for before you start. A payday loan is a short-term advance tied to your next paycheck, typically due in two to four weeks. An installment loan spreads repayment over several months, which makes the monthly payment smaller but the total interest higher. A personal loan from an online lender may have a longer term and a lower rate if your credit is decent. The right choice depends on how much you need, how quickly you can repay, and what your credit profile looks like. For a $2,000 vet bill, an installment loan is usually more manageable than a payday loan because you are not trying to repay the full amount in one paycheck.
If you are exploring emergency funding options, a platform that matches your request with multiple lenders can save you from applying to five different sites and triggering five hard credit inquiries. You can compare loan amounts, terms, and fees side by side before you commit. Just remember that the lender, not the matching platform, makes the final approval decision and sets the terms. Always read the loan agreement carefully, including the annual percentage rate, the repayment schedule, and any late fees. A loan you cannot repay on time will cost far more than the original vet bill.
For pet owners who need cash today, the practical steps look like this:
- Submit a short online request with your basic information and the amount you need.
- Review the loan offers presented by independent lenders, comparing APR and repayment terms.
- Choose the offer that fits your budget and complete the lender's verification process.
- Receive funds, often as soon as the next business day, and pay the veterinary clinic.
One important note: this route works best when you have a clear plan to repay the loan within the term. If your budget is already stretched thin, adding a loan payment can create a cycle of debt that is harder to escape than the original emergency. Use short-term financing as a bridge, not as a permanent solution.
Pet Insurance Reimbursement: Why It Does Not Help at the Front Desk
Pet insurance is a wonderful tool for managing long-term veterinary costs, but it is almost useless in the middle of an emergency. The reason is simple: most pet insurance policies operate on a reimbursement model. You pay the vet in full, submit a claim with the invoice and medical records, and the insurer reimburses you weeks later. Some companies process claims in five to ten days, but many take two to four weeks, and complex claims can take longer. The emergency clinic does not care about your policy; they care about payment at the time of service.
There are a few exceptions worth knowing. Some pet insurance companies now offer direct pay to the vet, but this is typically limited to specific veterinary networks and requires pre-approval, which is not realistic for an unplanned midnight visit. Others offer a pre-certification process for planned procedures, but an emergency by definition does not allow for that. If you already have pet insurance, you should still submit the claim after you pay, because the reimbursement will help you repay whatever loan or credit card you used. Just do not count on the insurer to solve the immediate cash problem.
If you do not have pet insurance, this emergency is a good reminder to look into it for the future. A policy with a reasonable deductible and a high annual limit can turn a $4,000 surgery into a manageable expense. But for tonight, you need a payment method that works now, not a reimbursement check that arrives after the crisis has passed.
Compare Your Options: Loan vs. Credit Card vs. Payment App
When you are standing at the front desk with a quote in your hand, you have three main categories of payment to compare: a short-term or personal loan, a credit card, and a payment app like CareCredit or Scratchpay. Each has trade-offs, and the best choice depends on your credit, your timeline, and how much you can afford to repay each month. A credit card is the fastest option if you have available credit, but the interest rate can be brutal if you carry a balance. A payment app designed for medical and veterinary expenses may offer promotional no-interest periods, but approval is not guaranteed and the application can take longer than swiping a card.
A short-term loan from a matched lender is often the best fit when you need a specific amount, want a fixed repayment schedule, and do not have enough credit card availability. The application is online, the decision can come quickly, and you know exactly what you owe and when. The downside is that the APR on short-term loans can be high, especially if your credit is imperfect. That is why comparing offers matters. A personal loan with a longer term may have a lower monthly payment, while a payday loan may be faster but far more expensive if you cannot repay it on time.
Here is a simple comparison to guide your decision:
- Credit card: Fastest if you have available credit, but high ongoing interest if you carry a balance.
- Payment app (CareCredit, Scratchpay): May offer no-interest promotional periods, but approval and application time vary.
- Short-term loan: Fast online application, fixed repayment schedule, but potentially high APR.
- Personal loan: Longer terms and possibly lower rates for good credit, but approval may take longer.
- Clinic payment plan: Often the cheapest option, but not every clinic offers one.
Before you choose, ask the clinic which payment methods they accept and whether they have a preference. Some clinics have relationships with specific financing partners and can help you apply on the spot. Others will simply hand you a tablet and let you choose. Either way, do not let urgency push you into an option you do not understand. Read the terms, check the APR, and make sure the monthly payment fits your budget.
Build a Fast-Action Plan Before the Next Emergency
The worst time to figure out how to pay a pet emergency vet bill is during the emergency itself. A little preparation goes a long way. Start by setting aside a small emergency fund specifically for pet care, even if it is just $500 to start. Next, research the emergency clinics in your area and ask about their payment policies before you need them. Do they offer payment plans? Which financing partners do they work with? Knowing this in advance saves precious minutes when every minute counts.
It also helps to understand your own financial options before you are under pressure. Check your credit score, know how much available credit you have, and look into whether you qualify for a personal loan or a line of credit. If you have pet insurance, keep your policy number and the claims phone number in your phone. If you do not, consider whether a policy makes sense for your pet's age and health. The goal is not to eliminate emergencies, because you cannot. The goal is to make sure that when one happens, you can focus on your pet instead of panicking about payment.
Finally, remember that you are not alone in this situation. Veterinary clinics see financial stress every day, and most are willing to work with you if you are honest and proactive. Ask for help, compare your options, and choose the path that lets you care for your pet without creating a financial crisis that lasts long after the bill is paid. CashLoanFunded