Personal Loans for Teachers on a Tight Budget: Smart Borrowing
Personal loans for teachers on a tight budget can cover urgent costs without wrecking your finances. Learn how to size, time, and compare offers wisely.
By Priya Dawson
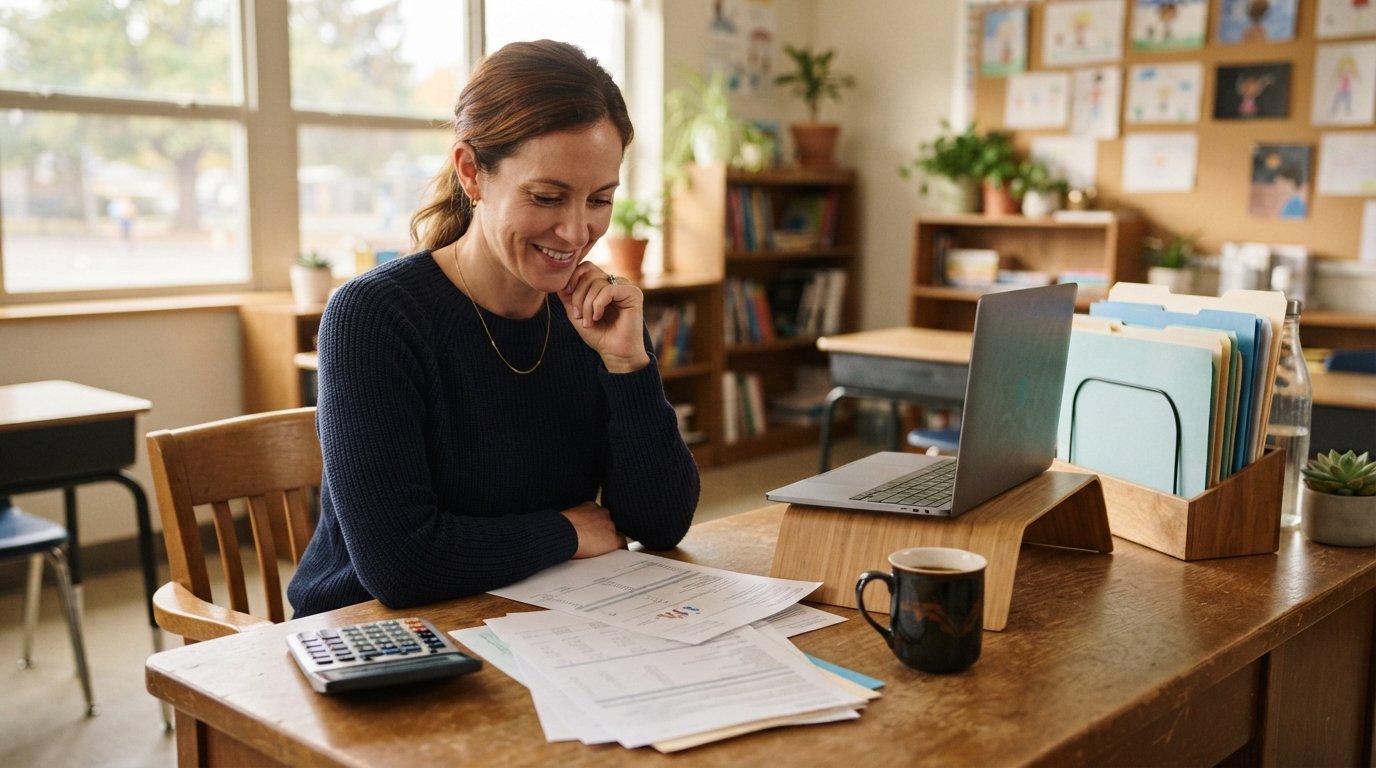
Teachers shape futures, yet their own financial picture often feels stretched thin. Between classroom supplies, summer income gaps, and unexpected home or car repairs, a tight budget can turn a minor emergency into a major stressor. When savings fall short, personal loans for teachers on a tight budget can offer a structured way to cover costs without derailing long-term goals. The key is approaching borrowing with the same careful planning you bring to lesson plans: know what you need, understand the terms, and match repayment to your actual pay schedule.
This guide walks through how teachers can evaluate personal loan options, prepare a strong application, and avoid the traps that turn a helpful loan into a financial burden. Whether you are facing a medical bill, a necessary home repair, or a summer cash-flow gap, the right approach can make borrowing a manageable tool rather than a source of anxiety.
Why Steady Salaried Income Works in Your Favor
Lenders look for evidence that you can repay what you borrow. A consistent salary from a school district, charter network, or private school provides exactly that signal. Even if your credit score is not perfect, a stable income history can offset some concerns. Many lenders view teachers as lower-risk borrowers because their employment tends to be predictable, with contracts that renew annually and pay schedules that follow a clear calendar.
That does not mean approval is guaranteed, but it does mean you have leverage. When you apply, highlight your employment tenure and the reliability of your district payroll. If you have been at the same school for several years, that continuity matters. Lenders also consider debt-to-income ratio, so keeping existing obligations modest improves your standing. For teachers with imperfect credit, a steady paycheck plus a clean recent payment history on rent or utilities can paint a stronger picture than a score alone suggests.
It also helps to understand how online lending marketplaces evaluate requests. Platforms like best online personal loans for fast approval connect borrowers with multiple lenders who may weigh income stability differently. Rather than relying on a single bank's criteria, you can submit one request and see offers from several sources, which is especially useful when your credit profile is mixed.
Match the Loan Size to the Actual Expense
One of the most common mistakes borrowers make is treating a loan approval as a shopping budget. If a lender approves you for $10,000 but your actual need is $3,500, borrowing the full amount means paying interest on money you do not need. Teachers on tight budgets should start by writing down the exact expense: the repair estimate, the medical bill balance, the tuition payment, or the summer income gap. Then borrow only what covers that figure, plus a small cushion for fees if necessary.
Here is a simple framework for setting your loan amount:
- List the specific expense and its confirmed cost (use written estimates or bills, not guesses).
- Subtract any savings or grants you can apply to the expense.
- Add a small buffer of 5 to 10 percent for unexpected fees or price changes.
- Compare that final number to the loan offers you receive, and choose the smallest amount that meets the need.
This approach keeps your monthly payment lower and reduces the total interest you pay over the life of the loan. It also protects your budget during months when school expenses, like classroom supplies or professional development fees, compete for your cash. Remember that a smaller loan is easier to repay early if your situation improves.
If you are exploring short-term options alongside personal loans, services like AdvanceCash can connect you with lenders for smaller, faster funding needs. These options may suit a shortfall that resolves within a few weeks, while a personal loan with a longer term better fits larger expenses that require months of repayment.
Time Repayment Around Your School-Year Pay Schedule
Many teachers receive paychecks only during the school year, with summer months either unpaid or covered through a deferred salary plan. If you are paid over ten months, your cash flow in July and August may look very different from October. When you compare loan offers, look at the due date and frequency of payments, not just the interest rate. A loan with a slightly higher rate but a due date that aligns with your payday may be far easier to manage than a cheaper loan that drafts on the wrong week.
Ask each lender whether you can choose your payment due date. Many online lenders allow you to set a date that matches your payroll schedule. If you are paid biweekly, consider whether a biweekly payment plan fits better than a single monthly draft. Also ask about deferment or hardship options in case a summer gap makes a payment difficult. Being upfront about your pay calendar helps you avoid late fees that can quickly erode the benefit of a low rate.
For teachers with 12-month pay, the calculation is simpler, but you should still map out your fixed expenses for the year. A personal loan payment should fit comfortably within your monthly surplus, not consume it entirely. A useful rule of thumb is to keep total debt payments, including the new loan, below 36 percent of your gross monthly income. If a loan pushes you past that line, consider a smaller amount or a longer term to reduce the monthly burden.
Documents Teachers Should Have Ready for a Fast Online Request
Speed matters when an expense is urgent, and a complete application prevents delays. Before you start an online request, gather the documents most lenders ask for. Having these ready can cut the time from application to funding down to a single business day in many cases.
- Government-issued photo ID, such as a driver's license or passport.
- Proof of income, including recent pay stubs or a district employment letter.
- Bank account details for direct deposit of funds and automatic payments.
- Social Security number for identity verification and credit checks.
- Contact information for your school or district HR office, in case employment verification is needed.
Some lenders may also ask for a utility bill or lease agreement to confirm your address. If you have a side job, tutoring income, or summer employment, gather documentation for that as well, since additional income can strengthen your application. Keep digital copies in a secure folder so you can upload them quickly. Avoid applying to many lenders in a short window, as multiple hard credit inquiries can temporarily lower your score. Instead, use a single marketplace request to see multiple offers with one inquiry where possible.
Compare Offers Side by Side Before You Commit
Not all personal loans are created equal, and the difference between two offers can amount to hundreds of dollars over a year. Create a simple comparison table with the same columns for each offer: interest rate (APR), loan term, monthly payment, origination fee, prepayment penalty, and total cost of credit. APR includes both interest and fees, so it is the best single number for comparing offers. A loan with a lower interest rate but a hefty origination fee may cost more than one with a slightly higher rate and no fee.
Read the fine print for prepayment penalties. If you expect a tax refund or summer pay to let you pay off the loan early, a prepayment penalty could erase your savings. Also check whether the lender reports to credit bureaus. On-time payments on a personal loan can help build your credit history, which is a valuable side benefit for teachers working to improve their financial profile. Finally, confirm the lender's customer service reputation and whether they offer any hardship programs. A lender that works with borrowers during tough months is worth a slightly higher rate.
Remember that personal loans for teachers on a tight budget should serve a specific purpose and have a clear repayment plan. Avoid using a loan to cover recurring expenses like groceries or utilities, which can signal a deeper budget imbalance. If you find yourself borrowing for routine costs, consider speaking with a nonprofit credit counselor or your district's employee assistance program for broader financial guidance.
With steady income, careful loan sizing, and repayment timed to your pay schedule, a personal loan can be a practical bridge over a temporary gap. Take the time to compare offers, gather your documents, and choose terms that fit your real budget, and you will turn a stressful moment into a manageable step toward financial stability.