Personal Loan for Self Employed Workers with Irregular Income
Learn how self-employed workers with irregular income can secure a personal loan by presenting bank statements, explaining gaps, and requesting the right amount.
By Hannah Adler
Your income as a self-employed worker can swing wildly from one month to the next. A strong quarter might be followed by a slow season, and traditional lenders often see that volatility as a red flag. But irregular income does not automatically disqualify you from borrowing. In fact, a growing number of lenders are willing to look beyond a simple paycheck and evaluate the full picture of your financial life. The key is knowing how to present your income in a way that builds lender confidence.
This guide walks you through the practical steps of securing a personal loan for self employed workers with irregular income. You will learn which documents matter most, how to frame your bank statements, why a smaller loan request can work in your favor, and how to explain income gaps without sinking your application. By the end, you will have a clear roadmap for approaching lenders with a stronger, more credible case.
Why Lenders Care About Income Stability (And How to Prove Yours)
Lenders are not trying to punish you for being self-employed. They are trying to answer one question: can you repay this loan on time, every month, even when work slows down? For salaried employees, a pay stub answers that question quickly. For you, it takes a bit more storytelling. The good news is that many lenders have adapted their underwriting to account for freelancers, contractors, gig workers, and small business owners.
What lenders really want is evidence of consistency over time. They want to see that your income, even if irregular, has a reliable floor. A freelance graphic designer who earns $8,000 in a good month and $3,000 in a slow month is still a stronger candidate than someone who earned $10,000 once and nothing since. Your job is to show that pattern clearly and honestly.
Documents Self-Employed Applicants Typically Need
Most lenders will ask for a combination of the following. Having these ready before you apply can speed up the process and signal that you are organized and serious.
- Two years of tax returns (personal and business, if applicable), including all schedules and attachments.
- Recent bank statements, usually three to twelve months, showing consistent deposits and cash flow.
- Profit and loss statements or a year-to-date income summary prepared by you or your accountant.
- Proof of business existence, such as a business license, 1099 forms, or client contracts.
- Government-issued ID and proof of address for identity verification.
If you do not have two full years of self-employment history, do not panic. Some lenders accept twelve months of bank statements or a strong year-to-date profit and loss statement. The important thing is to provide what you have, explain any gaps proactively, and avoid submitting incomplete or inconsistent paperwork. A clean, well-organized file goes a long way.
How to Present Bank Statements That Support Your Requested Amount
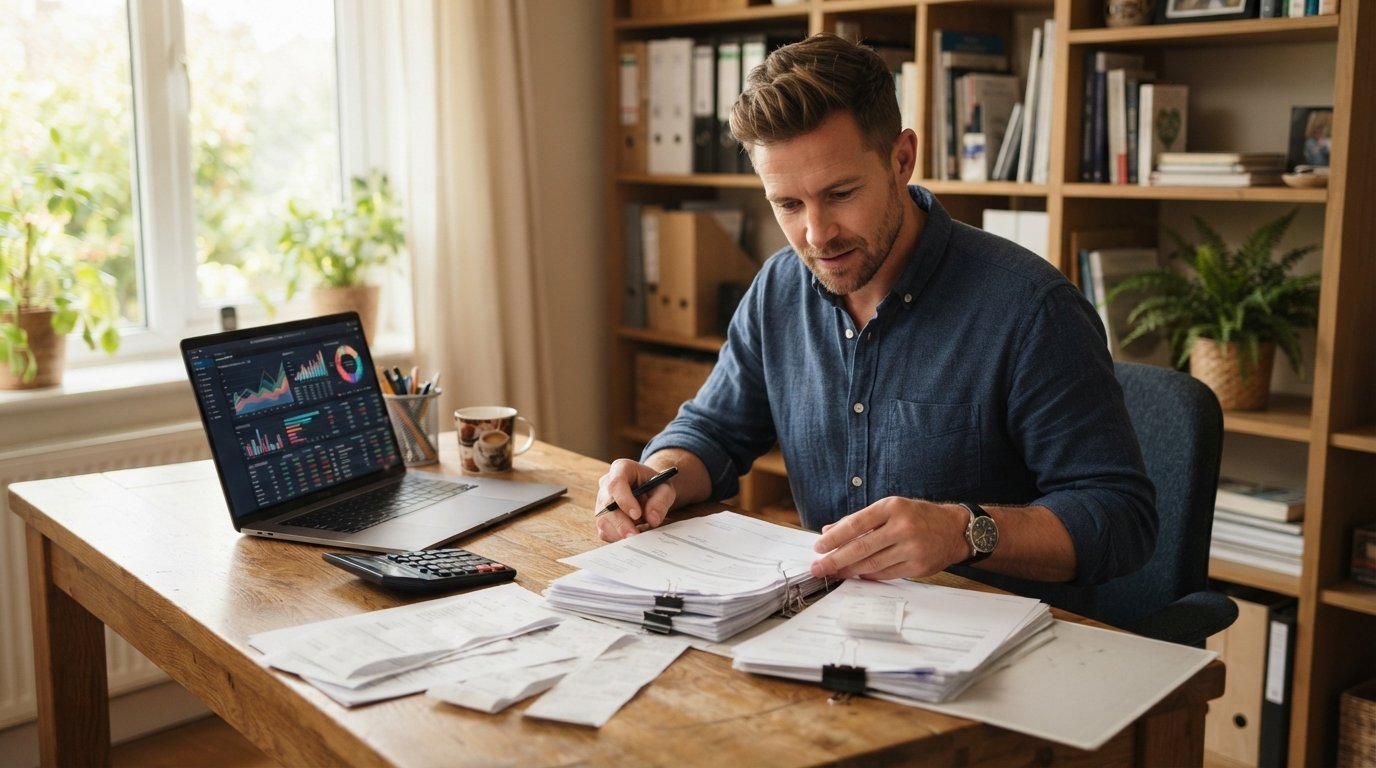
Bank statements are often the most persuasive tool in your application. They show real money moving in and out, not just what you reported on a tax return. But simply handing over a stack of statements is not enough. You need to help the lender see the story in the numbers.
Start by choosing a statement period that reflects your typical income pattern, not your worst month or your best month. If your income is seasonal, include a full twelve months so the lender can see the complete cycle. Highlight recurring deposits from clients or platforms, and use a simple cover letter or summary sheet to point out average monthly deposits, the lowest month, and how you covered expenses during slower periods. This turns raw data into a clear narrative.
It also helps to separate business and personal accounts. If you run everything through one account, consider opening a dedicated business checking account before you apply. Lenders can then see clean business deposits without personal transfers muddying the picture. If that is not possible, use colored highlights or a spreadsheet to label which deposits are business income and which are personal transfers or reimbursements.
Finally, be consistent. Do not cherry-pick three great months and hide the rest. Lenders will often ask for a longer history anyway, and inconsistency raises suspicion. Presenting a full, honest picture with a brief explanation of fluctuations builds trust and improves your odds.
Why a Smaller Loan Amount Can Improve Your Approval Odds
It is tempting to ask for the maximum amount you think you might need. But for irregular earners, a smaller loan request can be a strategic move. Lenders assess risk by comparing your requested loan amount to your demonstrated ability to repay. A $15,000 request might look risky against a $40,000 annual income with high variability, while a $5,000 request looks manageable and well within your means.
A smaller loan also gives you room to build a positive repayment history. Once you have made several on-time payments, you can often qualify for a larger amount or better terms on a future loan. Think of it as starting with a foot in the door rather than trying to kick it open. Many self-employed borrowers find that a modest first loan leads to much smoother approvals down the road.
If you need more than a small amount, consider whether you can combine a personal loan with other resources or phase your expenses. For urgent needs, a fast personal loan can provide quick funds while keeping the requested amount reasonable. The goal is to match your request to what your income can comfortably support, not to stretch for the maximum.
Explaining Income Gaps Without Hurting Your Case
Income gaps happen. Maybe you took a few months off to care for a family member, dealt with a health issue, or simply had a slow season. The worst thing you can do is ignore the gap and hope the lender does not notice. A short, honest explanation is almost always better than silence.
Frame the gap in terms of what you did to manage it and how you have recovered. For example: "I had a three-month gap in 2024 due to a planned sabbatical. I returned to full-time freelancing in March and have maintained consistent monthly deposits since." This shows self-awareness and responsibility. If the gap was due to an emergency, briefly explain the emergency and how it was resolved. Lenders are human, and many appreciate transparency.
Avoid over-explaining or sounding defensive. Keep it to two or three sentences, and focus on the present and future rather than dwelling on the past. If you have a strong recent history, that will carry more weight than a gap from two years ago. Pair your explanation with recent bank statements that show a stable or improving trend, and you will minimize the damage.
How ExpressCash Connects You with Lenders Who Understand Varied Income
Finding the right lender can feel like a full-time job, especially when your income does not fit a neat box. That is where a connection service like FundingCashLoans can help. Instead of applying to lender after lender and risking multiple hard credit pulls, you can submit one request and get matched with lenders who may be willing to consider your full financial picture.
ExpressCash is not a lender and does not make credit decisions. It is a free online service that connects U.S. consumers with a network of third-party lenders. The process is simple: you enter your details, get matched with lenders, and review any offers that come your way. There is no obligation to accept an offer, and the request typically takes less than five minutes. For self-employed workers with irregular income, this can be a more efficient way to see what options exist without committing to a single lender upfront.
Because ExpressCash works with lenders who consider a range of credit profiles, it can be a practical starting point when you need to explore personal loan options. Just remember that any loan terms, rates, and approval decisions come directly from the lender, not from ExpressCash. Always review the terms carefully before accepting an offer.
Practical Steps to Strengthen Your Application
Beyond the documents and explanations, there are several practical steps you can take to make your application more competitive. These are not gimmicks; they are simple habits that signal reliability to lenders.
- Separate business and personal finances. A dedicated business account makes your income easier to verify and reduces confusion.
- Keep a simple income log. Track deposits by client and date so you can quickly produce a summary if asked.
- Pay down existing debt. Lowering your debt-to-income ratio improves your perceived ability to repay a new loan.
- Save a small buffer. Even a few hundred dollars in savings shows you can absorb minor shocks without missing a payment.
- Check your credit report. Dispute errors and make sure your report accurately reflects your history before applying.
These steps take time, but they compound. A borrower who has separated accounts, kept clean records, and reduced debt will almost always have an easier time than one who has not. Start with one or two changes and build from there.
Understanding the Trade-Offs and Borrowing Responsibly
A personal loan can be a useful tool for managing irregular income, but it is not free money. Interest rates and fees can add up, especially if you choose a longer repayment term. Before you accept any offer, calculate the total cost of the loan, including all fees, and make sure the monthly payment fits comfortably within your lowest expected income month, not your highest.
It is also worth considering alternatives. If your need is not urgent, you might adjust your budget, negotiate payment plans with creditors, or tap into a small savings cushion. If your need is urgent, a short-term loan may be appropriate, but only if you have a clear plan to repay it. Responsible borrowing means borrowing what you can repay, not what you can qualify for.
Finally, keep your long-term goals in mind. Every on-time payment builds your credit and strengthens your future borrowing power. Every missed payment does the opposite. Treat your loan as a commitment, and it will serve you well.
Securing a personal loan for self employed workers with irregular income is entirely possible with the right preparation. Gather your documents, present your bank statements clearly, request a sensible amount, and explain any gaps honestly. With a little effort, you can turn a volatile income into a compelling case for approval.