How to Use a Line of Credit for Emergency Home Repairs
A line of credit can cover emergency home repairs fast, letting you draw only what you need and repay over time without draining savings.
By Olivia Bennett
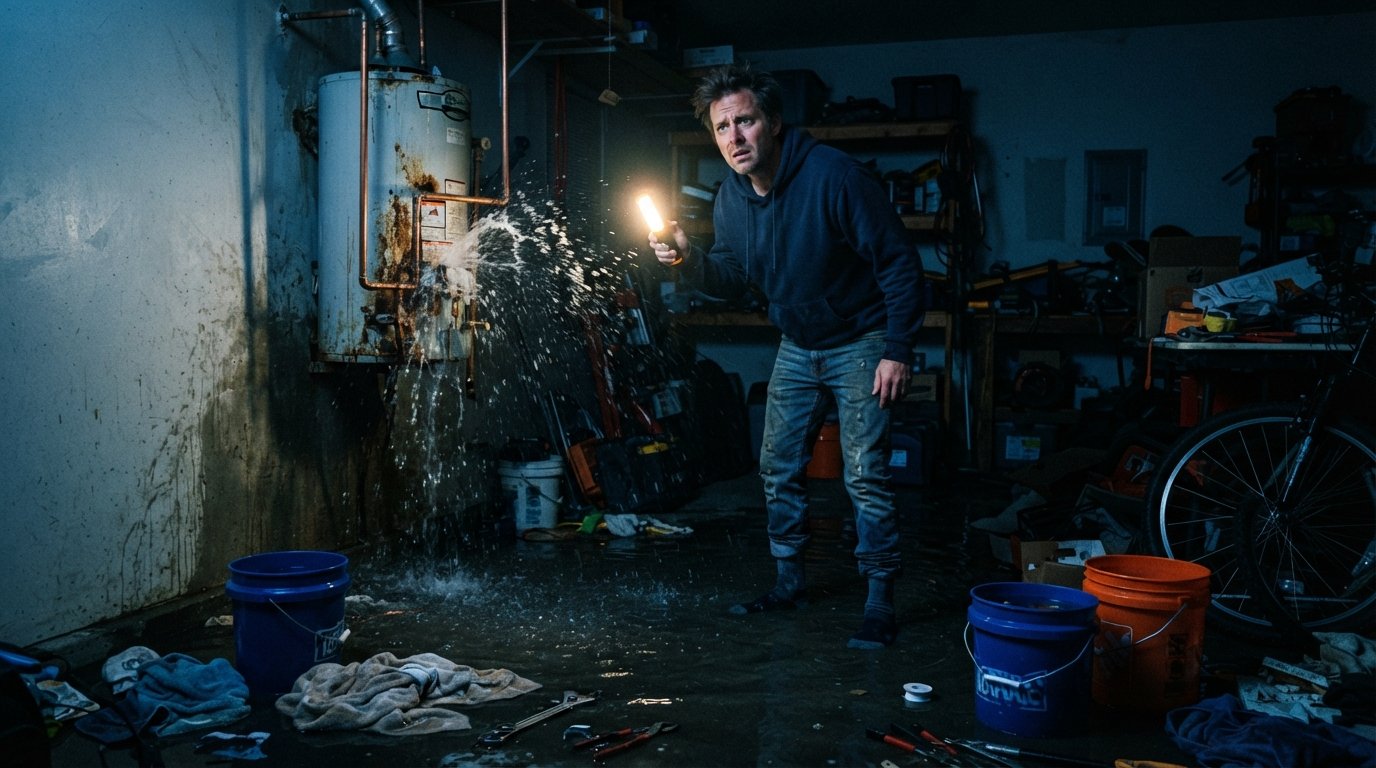
A burst pipe at 2 a.m. A failed water heater flooding the garage. A roof leak that turns a quiet Sunday into a scramble for buckets and tarps. Emergency home repairs rarely announce themselves, and they almost never wait for payday. When the damage is urgent and the bill is steep, a line of credit can give you a flexible way to cover the cost without draining every dollar in your savings account. Understanding how to use a line of credit for emergency home repairs, and when it makes sense versus other funding options, can mean the difference between a quick fix and a long-term financial headache.
Why Emergency Home Repairs Catch Homeowners Off Guard
Most homeowners plan for routine maintenance: gutter cleaning in the fall, HVAC tune-ups in the spring, maybe a fresh coat of paint every few years. What they cannot plan for is the sudden, expensive failure that demands immediate attention. According to housing industry data, the average emergency repair, whether it is a sewer line backup, a foundation crack, or an electrical panel failure, can run from several hundred to several thousand dollars. Very few households keep that kind of cash sitting idle in a savings account.
The problem is compounded by timing. Many emergencies happen outside normal business hours, which means emergency call-out rates, overtime labor, and premium pricing for parts. A plumber who would charge $200 during the day might charge $500 or more at midnight. Insurance may eventually reimburse part of the cost, but the homeowner still needs to pay upfront or authorize the work immediately.
That is where a line of credit becomes useful. Unlike a one-time lump-sum loan, a line of credit gives you a pool of available funds you can draw from as needed, repay, and draw from again. For homeowners facing a repair that might cost more than the initial estimate, or a series of related repairs, that flexibility matters. You are not locked into borrowing a fixed amount and paying interest on money you have not yet used.
What a Line of Credit Actually Is and How It Works
A line of credit is a revolving credit facility. The lender approves you for a maximum limit, say $10,000, and you can borrow against that limit whenever you need to. Interest is typically charged only on the amount you actually draw, not the full limit. As you repay the principal, your available credit goes back up, similar to how a credit card works but often with a lower interest rate and higher borrowing limit.
There are several types of lines of credit a homeowner might use for emergency repairs:
- Personal line of credit: Unsecured, based on your creditworthiness, and not tied to your home equity. Faster to obtain but may have higher rates.
- Home equity line of credit (HELOC): Secured by your home, often with lower rates, but requires equity and a longer approval process.
- Credit card line of credit: Convenient but typically the highest interest rate and lowest limit among the three.
- Store or contractor financing: Offered by some home improvement retailers and service providers, often with promotional periods but deferred interest traps.
For emergency repairs, the key advantage of a line of credit is speed combined with flexibility. You can get approved for a limit, then use only what you need when you need it. If the contractor discovers additional damage once the walls are open, you have room to borrow more without submitting a new application.
How to Use a Line of Credit for Emergency Home Repairs: A Step-by-Step Approach
Using a line of credit effectively requires more than just swiping a card or writing a check. You need a plan for how you will draw the funds, how you will repay them, and how you will avoid turning a short-term emergency into a long-term debt problem. Here is a practical framework.
Step 1: Assess the true cost of the repair. Before you borrow anything, get at least one written estimate, ideally two if time allows. Emergency repairs often come with surprises, so ask the contractor for a best-case and worst-case range. If the repair is covered by insurance, find out what your deductible is and whether the insurer will pay you directly or reimburse you later. Knowing the full financial picture prevents you from borrowing too little or too much.
Step 2: Check your existing credit options. If you already have a personal line of credit, HELOC, or a credit card with a reasonable limit, you may not need to apply for anything new. Using an existing line of credit is faster and avoids a hard credit inquiry. However, if your existing lines are maxed out or have high interest rates, a new line of credit might be worth exploring.
Step 3: Compare offers from multiple lenders. If you need a new line of credit, do not accept the first offer that comes your way. Rates, fees, and repayment terms vary widely. Some lenders charge an annual fee, a draw fee, or a prepayment penalty. Others offer promotional rates for the first six or twelve months. For emergency repairs, you want a line with no prepayment penalty so you can pay it off early without extra cost.
If you are concerned about qualifying with a less-than-perfect credit score, platforms like ExpressCash bad credit options can help you explore lenders who work with a range of credit profiles. ExpressCash is a connector service, not a direct lender, and it matches your loan request with a network of third-party lenders who may offer lines of credit or other short-term funding options. The application takes less than five minutes and does not obligate you to accept any offer.
Step 4: Draw only what you need, when you need it. One of the biggest mistakes homeowners make with a line of credit is drawing the full amount upfront and letting it sit in a checking account. Remember, interest accrues on the outstanding balance, not the available limit. If the contractor needs a $2,000 deposit today and the rest upon completion, draw only the deposit. Keep the remaining credit available for the final payment or for any unexpected extras.
Step 5: Pay more than the minimum whenever possible. A line of credit can be a useful tool, but it can also become a debt trap if you only make minimum payments. Interest charges add up quickly, especially on unsecured lines. Aim to pay off the balance within six to twelve months. If you received an insurance reimbursement, apply it directly to the line of credit as soon as it arrives.
Step 6: Keep the line open for future emergencies. Once you have paid off the balance, resist the urge to close the account. Having an open line of credit with a zero balance is a financial safety net. It costs nothing to maintain (unless there is an annual fee) and gives you immediate access to funds if another emergency strikes.
Comparing a Line of Credit to Other Emergency Funding Options
A line of credit is not the only way to pay for an emergency home repair. Depending on your situation, other options might be faster, cheaper, or more appropriate. Here is how a line of credit stacks up against common alternatives.
- Credit card: Fast and convenient, but interest rates are often above 20 percent. A line of credit typically offers a lower rate and a higher limit.
- Personal loan: A lump sum with a fixed repayment schedule. Good for predictable costs, but less flexible if the repair cost changes.
- Home equity loan: A second mortgage with a fixed rate and fixed term. Lower rates than unsecured options, but closing costs and a longer approval timeline.
- Contractor financing: Convenient, but promotional offers often come with deferred interest that retroactively applies if you do not pay off the balance in time.
- Savings or emergency fund: The ideal option if you have the cash. No interest, no debt, no application process.
For many homeowners, the decision comes down to speed versus cost. A line of credit is usually faster than a home equity loan and cheaper than a credit card. It offers more flexibility than a personal loan. The trade-off is that unsecured lines of credit may have higher rates than secured options, and secured lines like HELOCs take longer to set up.
If you are exploring short-term borrowing options and want to see what lenders in your area might offer, you can submit a request through 4Payday to compare offers from multiple lenders. The platform is designed for consumers who need fast access to funds and want to review options without a hard credit pull upfront.
When a Line of Credit Is the Right Choice for a Home Emergency
A line of credit makes the most sense when the repair cost is uncertain, when you need funds quickly, and when you can repay the balance within a reasonable timeframe. For example, if a tree falls on your roof and the contractor cannot give you a final price until they inspect the damage from the inside, a line of credit lets you authorize the work and pay as the scope becomes clear. If you have insurance, you can use the line to cover the deductible and upfront costs, then repay it when the claim is settled.
It is also a good fit for homeowners who have equity but do not want to go through the full HELOC process. A personal line of credit from an online lender can be approved in minutes and funded as soon as the next business day, depending on the lender. That speed matters when a repair cannot wait.
On the other hand, a line of credit may not be the best choice if you are already carrying high-interest debt, if you have no clear plan to repay the balance, or if the repair cost is small enough to cover with cash. In those cases, a credit card with a zero percent introductory offer or a small personal loan might be more appropriate.
Mistakes to Avoid When Using a Line of Credit for Home Repairs
Even a well-intentioned borrowing decision can go wrong if you overlook a few key details. Here are the most common mistakes homeowners make when using a line of credit for emergency repairs, and how to avoid them.
- Borrowing more than you need. Just because you are approved for $15,000 does not mean you should draw $15,000. Borrow only what the repair requires, plus a small buffer for unexpected costs.
- Ignoring the repayment terms. Some lines of credit have interest-only payment periods, which keep monthly payments low but do not reduce the principal. Read the terms carefully and understand when the full repayment kicks in.
- Using a line of credit for discretionary upgrades. An emergency repair is not the time to add granite countertops or upgrade to a tankless water heater unless that upgrade is necessary for the repair itself. Keep the scope tight.
- Failing to communicate with your insurer. If the repair is covered by insurance, file the claim before you borrow. Some insurers have preferred contractors and may negotiate a lower rate, reducing your out-of-pocket cost.
- Not shopping around. Rates and terms vary significantly between lenders. A difference of a few percentage points can cost you hundreds of dollars over the life of the line.
Avoiding these mistakes starts with a clear plan. Before you draw a single dollar, write down the total repair cost, your repayment timeline, and the maximum monthly payment you can afford. If the numbers do not work, consider a different funding option or a phased approach to the repair.
Building a Financial Safety Net for Future Home Emergencies
Once the immediate crisis is over, take steps to prepare for the next one. An emergency fund dedicated to home repairs can prevent you from relying on credit in the future. Aim to set aside one to three percent of your home's value each year for maintenance and repairs. For a $300,000 home, that is $3,000 to $9,000 annually, which may sound like a lot, but even small monthly contributions add up over time.
In addition to savings, consider maintaining an open line of credit as a backup. Even if you never use it, having access to funds can give you peace of mind and negotiating power. You can also review your homeowners insurance policy to make sure you have adequate coverage for common emergencies like water damage, roof leaks, and electrical failures. Some policies offer add-on coverage for specific perils, which can reduce your out-of-pocket costs if disaster strikes.
Finally, keep a list of trusted contractors and service providers on hand. When an emergency happens, you do not want to waste time searching for a reputable plumber or electrician. Having a few names ready can speed up the repair process and help you get accurate estimates faster.
Emergency home repairs are stressful, but they do not have to derail your finances. By understanding how to use a line of credit for emergency home repairs, comparing your options, and borrowing responsibly, you can handle the unexpected without sacrificing your long-term financial stability. Whether you turn to a personal line of credit, a HELOC, or a connector service like ExpressCash to explore lender offers, the key is to have a plan before the next crisis hits.