How to Tell a Real Loan Offer From a Scam Call
Spot loan scam calls before sharing your data. Call 8338560496 for help finding trusted lenders and real offers.
By Sophia Miller
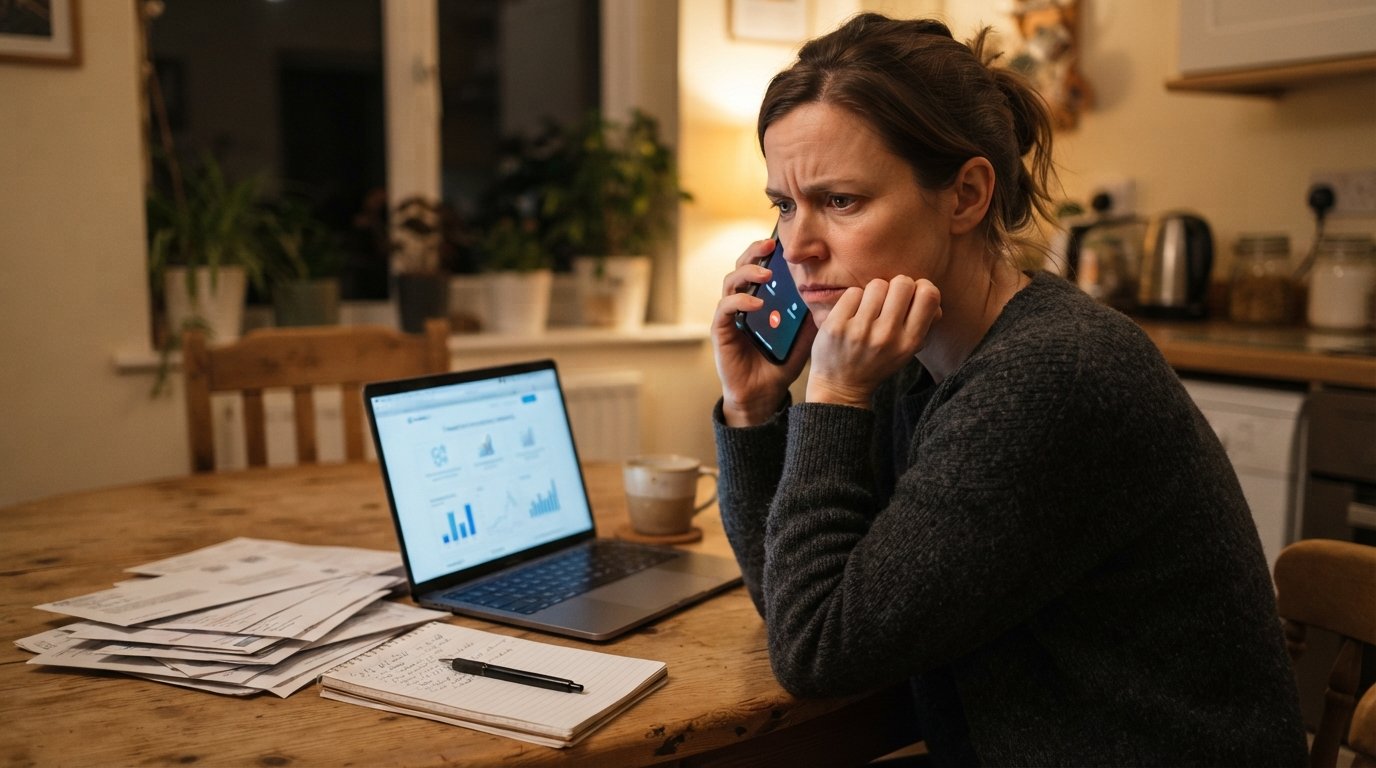
Your phone rings, and the caller claims you have been pre-approved for a loan. The offer sounds perfect: fast cash, no credit check, guaranteed approval. But before you share your Social Security number or pay any fee, you need to know whether that call is legitimate. Scammers have become increasingly sophisticated, using spoofed numbers and convincing scripts to steal money and personal data. Learning how to tell a real loan offer from a scam call is one of the most valuable financial skills you can develop, especially when you are in a hurry to cover an unexpected expense.
This guide breaks down the specific red flags, verification steps, and legal protections that separate genuine lenders from fraudsters. Whether you are dealing with medical bills, car repairs, or another emergency, understanding these differences will help you protect yourself while still finding the funding you need.
Why Loan Scam Calls Have Become So Common
The rise of loan scam calls tracks closely with advances in technology that make it cheap and easy for fraudsters to reach thousands of people at once. Voice over IP services, caller ID spoofing apps, and automated dialing systems allow scammers to mask their true location and identity. They can make a call appear to come from a local area code or even from a bank you recognize.
At the same time, economic pressure pushes many consumers to search for fast cash. When people are desperate for money, they may overlook warning signs that would normally raise suspicion. Scammers exploit this urgency by creating a sense of panic: the loan is only available today, the rate will expire in an hour, or you must act immediately to secure funds.
Another factor is the sheer volume of legitimate loan offers that arrive by phone. Many real lenders and loan matching services do contact consumers by phone, which makes it harder to distinguish a genuine call from a fraudulent one. The key is not to avoid all calls but to know what a legitimate offer looks like and what a scam looks like.
According to the Federal Trade Commission, impostor scams and advance-fee loan scams consistently rank among the top categories of consumer fraud. The agency receives thousands of complaints each year from people who paid upfront fees for loans that never materialized or who shared personal information that was later used for identity theft.
Red Flags That Signal a Loan Scam Call
The most reliable way to protect yourself is to recognize the warning signs before you share any information or send any money. Scammers often reveal themselves through a combination of pressure tactics, unusual requests, and vague or contradictory details about the loan terms.
One of the clearest indicators is a demand for payment before you receive the loan. Legitimate lenders deduct fees from the loan proceeds or charge them as part of the closing process. They do not ask you to wire money, buy gift cards, or send a prepaid debit card to cover insurance, processing, or a so-called good faith deposit. If a caller insists on upfront payment, that is almost certainly a scam.
Another red flag is a guarantee of approval regardless of your credit history. Real lenders evaluate creditworthiness and other factors before making an offer. If a caller promises approval for everyone, or claims that your bad credit does not matter at all, they are likely trying to lower your guard.
Additional warning signs include:
- The caller asks for your Social Security number, bank account details, or online banking password before you have seen any written terms.
- The offer comes with extreme pressure to act immediately, such as a threat that the funds will be released to someone else if you do not decide within minutes.
- The caller cannot or will not provide a physical address, a company website, or a state lending license number.
- You are asked to pay using a method that is difficult to trace or reverse, such as gift cards, wire transfers, or cryptocurrency.
- The caller claims to represent a government agency or a well-known bank but uses a generic greeting and cannot answer basic questions about the institution.
If you notice even one of these signs, end the call. Do not provide any personal information, and do not call back the number that appeared on your caller ID. Instead, look up the company independently using a trusted source.
How to Verify a Loan Offer Before You Commit
Verification is the single most effective defense against loan scams. Even if a call sounds professional and the caller seems knowledgeable, you should always take steps to confirm that the offer is real before sharing sensitive information or making any payment.
Start by asking the caller for the full legal name of the lending company, its physical address, and its state lending license number. Legitimate lenders are required to be licensed in the states where they operate, and they should be able to provide this information without hesitation. Write down what they tell you, then hang up and verify it independently.
Use the following steps to confirm a loan offer:
- Search for the company name online along with the words "scam" or "complaint" to see if other consumers have reported problems.
- Check your state's financial regulatory website or the Nationwide Multistate Licensing System to confirm that the lender holds a valid license.
- Look for a legitimate company website that lists a physical address, phone number, and privacy policy.
- Call the company back using a phone number you find on its official website, not the number the caller gave you.
- Ask for written loan terms, including the annual percentage rate, fees, repayment schedule, and total cost of the loan, before you agree to anything.
A legitimate lender will never rush you past these steps. In fact, responsible lenders encourage you to review the terms carefully and ask questions. If a caller becomes irritated or evasive when you ask for verification, that is a strong signal that something is wrong.
If you are exploring short-term loan options, working with a reputable connection service can reduce your exposure to fraud. Platforms like 4Payday connect consumers with independent lenders and provide educational resources about responsible borrowing. ExpressCash operates in a similar way, matching loan requests with a network of third-party lenders rather than making loans directly. Using a service that clearly discloses its role and connects you with licensed lenders is far safer than responding to an unsolicited call from an unknown party.
What Real Lenders Do Differently
Understanding the legitimate loan process helps you recognize when a call does not follow the normal pattern. Real lenders and loan matching services operate within a legal framework that requires transparency, fair lending practices, and respect for consumer privacy.
When you submit a loan request through a legitimate platform, you typically fill out an online form with your basic information. The platform then matches your request with one or more lenders in its network. Those lenders review your information and may present you with an offer that includes the loan amount, interest rate, fees, and repayment terms. You are under no obligation to accept the offer.
Real lenders do not ask for upfront fees before disbursing funds. They do not threaten you or pressure you into making a split-second decision. They provide written disclosures that comply with the Truth in Lending Act, which requires clear information about the cost of credit. They also follow the Fair Debt Collection Practices Act when collecting payments, which means they do not harass you or use deceptive tactics.
If you are looking for refinancing options, you can compare legitimate offers through resources like our guide on best refinance loan offers, which explains how to evaluate rates and terms. The same principles apply: legitimate lenders compete for your business by offering transparent terms, not by using high-pressure tactics.
Legal Protections Against Loan Scams
Several federal and state laws exist to protect consumers from fraudulent lending practices. Knowing your rights can help you recognize when a caller is violating the law and give you confidence to report suspicious activity.
The Truth in Lending Act requires lenders to disclose key terms before you sign, including the annual percentage rate and finance charges. The Fair Credit Reporting Act governs how your credit information can be used and gives you the right to dispute inaccurate information. The Equal Credit Opportunity Act prohibits discrimination in lending based on race, color, religion, national origin, sex, marital status, age, or receipt of public assistance.
At the state level, payday lending and installment lending are regulated by agencies that license lenders and investigate complaints. If you believe you have been targeted by a loan scam, you can file a complaint with your state attorney general's office, the Consumer Financial Protection Bureau, or the Federal Trade Commission. Reporting the scam helps authorities track down fraudsters and may prevent others from becoming victims.
It is also worth noting that legitimate lenders will never ask you to lie on a loan application or to falsify documents. If a caller suggests that you inflate your income or provide false information to qualify, they are not acting in your best interest and may be setting you up for legal trouble.
What to Do If You Think You Have Been Targeted
If you suspect that a loan offer call is a scam, the first step is to stop communicating with the caller. Do not provide any additional information, and do not send money. If you have already shared personal or financial information, take immediate steps to protect yourself.
Contact your bank and credit card companies to alert them to potential fraud. You may want to place a fraud alert or freeze on your credit reports with the three major credit bureaus: Equifax, Experian, and TransUnion. A credit freeze prevents new accounts from being opened in your name without your permission, which can stop identity thieves from taking out loans or opening credit cards using your information.
Change any passwords that you may have shared, especially for online banking and email accounts. Monitor your bank statements and credit reports closely for unauthorized activity. If you discover fraudulent charges or accounts, report them immediately and dispute them in writing.
Finally, report the scam to the appropriate authorities. The more information you can provide, such as the caller's phone number, the company name they used, and any details about what they asked you to do, the more helpful your report will be. Even if the scammer is never caught, your report contributes to a larger effort to protect consumers.
Building Healthy Borrowing Habits
Prevention is ultimately about developing habits that make you less vulnerable to scams. When you need to borrow money, start by researching your options through trusted sources. Use reputable comparison tools and read reviews from other consumers. Avoid responding to unsolicited calls, emails, or text messages that promise easy money.
Before you agree to any loan, make sure you understand the total cost, including interest and fees. Ask yourself whether you can realistically repay the loan on time. If the answer is uncertain, consider alternatives such as negotiating a payment plan with your creditor, seeking help from a nonprofit credit counseling agency, or exploring emergency assistance programs in your community.
If you do decide to pursue a short-term loan, choose a lender or connection service that is transparent about its role and provides clear, written terms. ExpressCash, for example, connects consumers with independent lenders and emphasizes a secure, no-obligation process. You can submit a request online in minutes and review any offers you receive without pressure. That kind of transparency is the hallmark of a legitimate service.
Remember that no legitimate lender will ever ask you to pay upfront for a loan or guarantee approval without checking your credit. By staying informed and verifying every offer, you can protect your finances and your peace of mind.