How to Recover Financially After Taking a Short Term Loan
Rebuild your financial stability after a short term loan with a clear repayment plan, emergency savings, and credit repair strategies.
By Sophia Miller
Taking out a short term loan can feel like a lifeline when an unexpected expense hits, but once the immediate crisis passes, many borrowers find themselves facing a new challenge: rebuilding their financial stability. The relief of having cash in hand quickly gives way to the reality of repayment schedules, fees, and the impact on your budget. If you are wondering how to recover financially after taking a short term loan, you are not alone. Millions of Americans use these products each year, and many successfully bounce back with a clear plan and disciplined execution.
The good news is that recovery is entirely achievable. It requires a shift in mindset from survival mode to strategic rebuilding. You need to understand exactly what you owe, create a realistic path to pay it off, and take steps to prevent finding yourself in the same position again. This guide will walk you through the process step by step, offering practical advice you can apply today.
Assess Your Current Financial Situation Honestly
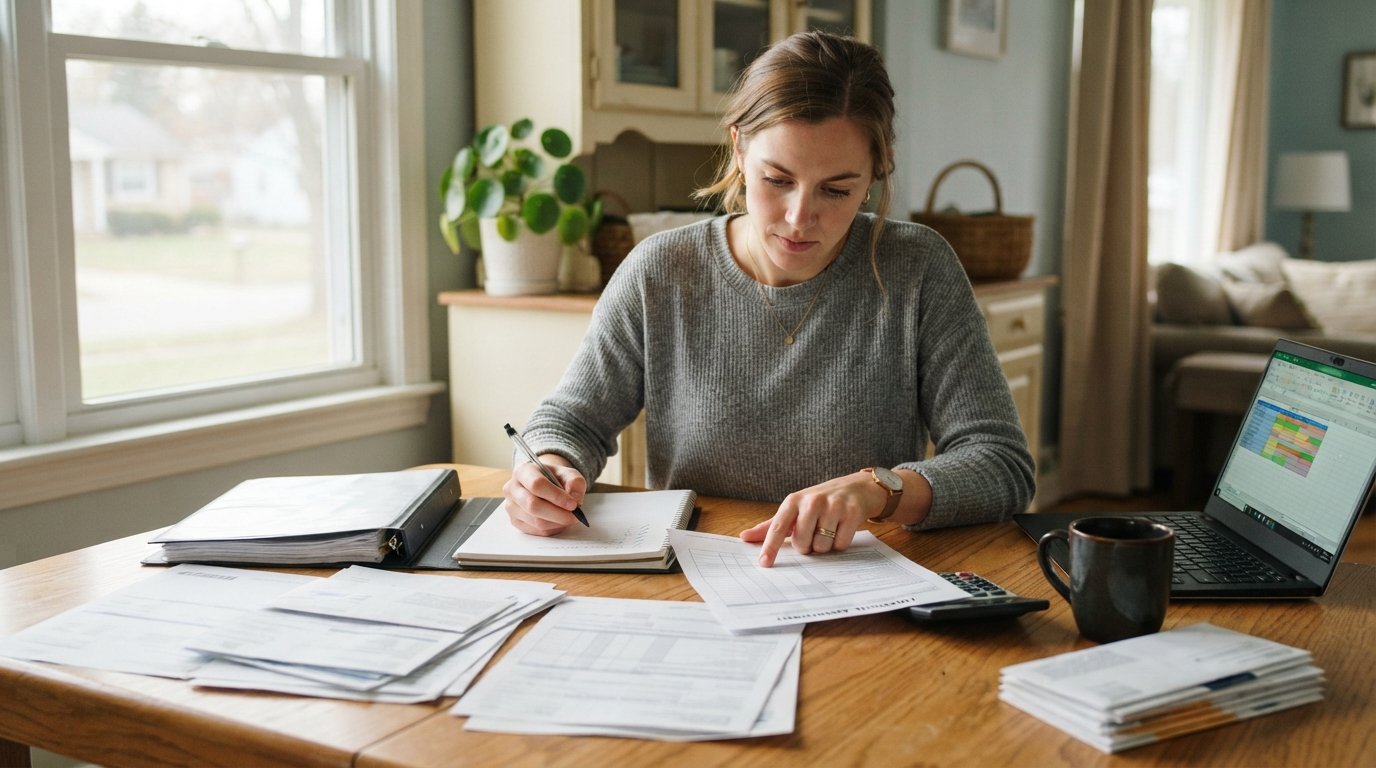
Before you can move forward, you need a clear picture of where you stand. Gather all your loan documents, bank statements, and any correspondence from your lender. Write down the total amount you owe, the interest rate or finance charge, the due dates, and any fees associated with the loan. If you have multiple short term loans, list each one separately. This exercise can be sobering, but it is essential. You cannot fix what you do not fully understand.
Next, calculate your monthly income and your essential expenses: rent or mortgage, utilities, groceries, transportation, and insurance. Subtract your expenses from your income to see what is left. If the number is negative or very small, you will need to make adjustments. This might mean cutting discretionary spending, taking on extra hours at work, or finding a side gig. The goal is to free up as much cash as possible to put toward your debt.
Consider using a simple spreadsheet or a budgeting app to track everything. Seeing the numbers in front of you can be motivating and help you prioritize. If you are unsure where to start, many financial experts recommend the 50/30/20 rule: 50 percent of income for needs, 30 percent for wants, and 20 percent for savings and debt repayment. While this ratio may be difficult to achieve initially, it provides a useful target.
Prioritize Your Debts and Create a Repayment Plan
Not all debts are created equal. Short term loans often come with very high interest rates, so paying them off quickly should be a top priority. If you have multiple debts, consider which one to tackle first. Two common strategies are the snowball method (paying off the smallest balance first for psychological wins) and the avalanche method (paying off the highest interest rate first to save money). Both work, so choose the one that keeps you motivated.
Contact your lender to discuss your situation. Many lenders are willing to work with borrowers who are proactive and honest about their circumstances. You might be able to negotiate a payment plan, extend the due date, or even reduce fees. Do not wait until you miss a payment to reach out. Communication is key.
If you are struggling to manage multiple payments, a debt consolidation loan might be an option. This involves taking out a new loan to pay off your existing debts, ideally at a lower interest rate. However, be cautious: if you cannot qualify for a lower rate, consolidation could make things worse. Alternatively, a nonprofit credit counseling agency can help you create a debt management plan and negotiate with creditors on your behalf.
Here are some steps to build your repayment plan:
- List all debts with balances, interest rates, and minimum payments.
- Decide on a strategy: snowball or avalanche.
- Allocate as much extra money as possible to the target debt.
- Make on-time payments on all other debts to avoid late fees.
- Review your progress monthly and adjust as needed.
Remember that consistency matters more than perfection. Even small extra payments can add up over time. If you receive a windfall, such as a tax refund or bonus, consider putting it directly toward your loan balance.
Build an Emergency Fund to Break the Cycle
One of the main reasons people turn to short term loans is a lack of emergency savings. Without a cushion, any unexpected expense becomes a crisis. To recover financially and avoid future borrowing, you need to build an emergency fund. Start small: aim to save $500, then $1,000, and eventually enough to cover three to six months of essential expenses.
Open a separate savings account specifically for emergencies. This makes it less likely that you will dip into it for non-urgent purchases. Automate your savings by setting up a recurring transfer from your checking account on payday. Even $20 per week can grow into a meaningful buffer over time.
If you receive irregular income, such as from freelance work or gig economy jobs, adjust your savings strategy accordingly. Save a percentage of each payment you receive. The key is to make saving a habit, not an afterthought. Once you have a cushion, you will be less vulnerable to the high costs of short term loans.
Improve Your Credit Score and Financial Health
Short term loans can negatively impact your credit score, especially if you miss payments or default. Rebuilding your credit takes time, but it is one of the most important steps toward long-term financial recovery. Start by checking your credit reports for errors and disputing any inaccuracies. You are entitled to free reports from each major bureau annually.
Pay all your bills on time, every time. Payment history is the single biggest factor in your credit score. If you have credit cards, keep your balances low relative to your limits. Consider using a secured credit card if you cannot qualify for a traditional one. Use it for small purchases and pay it off in full each month to build positive history.
As you improve your credit, you may gain access to better loan products with lower interest rates. This can make future borrowing less expensive and reduce the risk of falling into a debt trap. In the meantime, if you need to explore loan options, platforms like ExpressCash can help you understand how to speed up funding approval for short term loans and connect with lenders who may work with a range of credit profiles.
Additionally, consider working with a financial coach or taking free online courses to improve your money management skills. Understanding topics like budgeting, saving, and investing can empower you to make better decisions and avoid the pitfalls that led to short term borrowing in the first place.
Avoid Common Pitfalls After a Short Term Loan
Once you have repaid your short term loan, it is tempting to revert to old habits. However, this is the time to be extra vigilant. Avoid taking out new loans unless absolutely necessary, and never borrow more than you can afford to repay. Payday loans and similar products are designed to be short term solutions, not long term fixes.
Be wary of rollover offers. Many lenders allow you to roll over your loan for an additional fee, but this can lead to a cycle of debt that is hard to escape. If you cannot repay your loan on time, seek help rather than rolling it over. Talk to your lender, a credit counselor, or a trusted friend or family member.
Also, be cautious of scams that target people with poor credit. If a lender promises guaranteed approval or asks for upfront fees, it is likely a scam. Legitimate lenders will check your credit and disclose all terms clearly. Always read the fine print and never sign anything you do not understand.
For those seeking short term loan options, 4Payday connects consumers in the United States with lenders offering payday loans, personal loans, and installment loans. The platform facilitates loan request submissions and provides educational resources about responsible borrowing. It is designed for individuals seeking quick access to funds, but it is crucial to borrow responsibly and have a repayment plan in place.
Create a Long-Term Financial Strategy
Recovering financially after a short term loan is not just about paying off the debt; it is about building a more secure future. Start by setting specific, measurable financial goals. These could include paying off all high-interest debt, saving a certain amount for retirement, or buying a home. Write your goals down and review them regularly.
Develop a budget that aligns with your goals and values. Track your spending for a month to see where your money actually goes. You might be surprised at how much you spend on small, unnecessary items. Redirect that money toward savings or debt repayment.
Consider increasing your income through a side hustle, freelance work, or asking for a raise at your job. Even an extra $100 per week can make a significant difference in your financial trajectory. Invest in yourself by learning new skills that can lead to higher-paying opportunities.
Finally, protect yourself with adequate insurance. Health insurance, auto insurance, and renters or homeowners insurance can prevent small emergencies from becoming financial catastrophes. Review your policies annually to ensure they meet your needs and shop around for better rates if possible.
Recovering from a short term loan requires patience, discipline, and a willingness to change your financial habits. By assessing your situation, prioritizing debt repayment, building an emergency fund, and improving your credit, you can break the cycle and achieve lasting stability. Remember that setbacks are temporary, and with the right plan, you can regain control of your finances and move forward with confidence.