How to Qualify for a Loan When Paid in Cash or Tips
Turn cash and tip income into loan approval. Learn how to qualify for a loan when paid in cash or tips with bank statements and tax returns.
By Mia Turner
Getting paid in cash or tips gives you immediate spending power, but it can feel like a hidden barrier when you need to borrow money. Lenders want proof of steady income, and a stack of receipts or a cash-filled envelope does not automatically translate into a verifiable paycheck. If you are a server, bartender, rideshare driver, hairstylist, or anyone else whose income arrives in small bills, you may wonder whether a traditional or online loan is even possible. The good news is that qualifying for a loan when paid in cash or tips is absolutely achievable. You simply need to document your earnings the same way a salaried employee documents a W-2. This guide walks you through the practical steps, the paperwork that matters, and how to present your cash-based income in a way that lenders can trust.
Why Cash and Tip Income Creates a Qualification Gap
Most lenders rely on automated verification systems that pull data from payroll databases or tax transcripts. When your income does not flow through a standard payroll processor, those systems come up empty. That does not mean you are out of options. It means you need to build your own paper trail. The core issue is not the source of your money; it is the ability to prove it exists, that it is consistent, and that it will continue.
Cash income often goes unreported, which creates a second problem. If you have been depositing tips into your bank account but not claiming them on your taxes, lenders may still count your deposits as income, but the amounts will look smaller than what you actually earn. On the other hand, if you report your tips on your tax return, you have an official record that carries weight with underwriters. The strongest position is a combination of reported income and consistent bank deposits.
Different loan types have different tolerance levels for cash income. Payday loans and short-term installment loans often rely on bank statements and pay stubs, but some lenders in that space are more flexible. Personal loans from online lenders may use bank account data to verify deposits. Auto loans and mortgages are stricter, usually requiring tax returns and sometimes profit-and-loss statements. Knowing which type of loan you are pursuing helps you prepare the right documents.
Build a Bankable Paper Trail for Cash and Tips
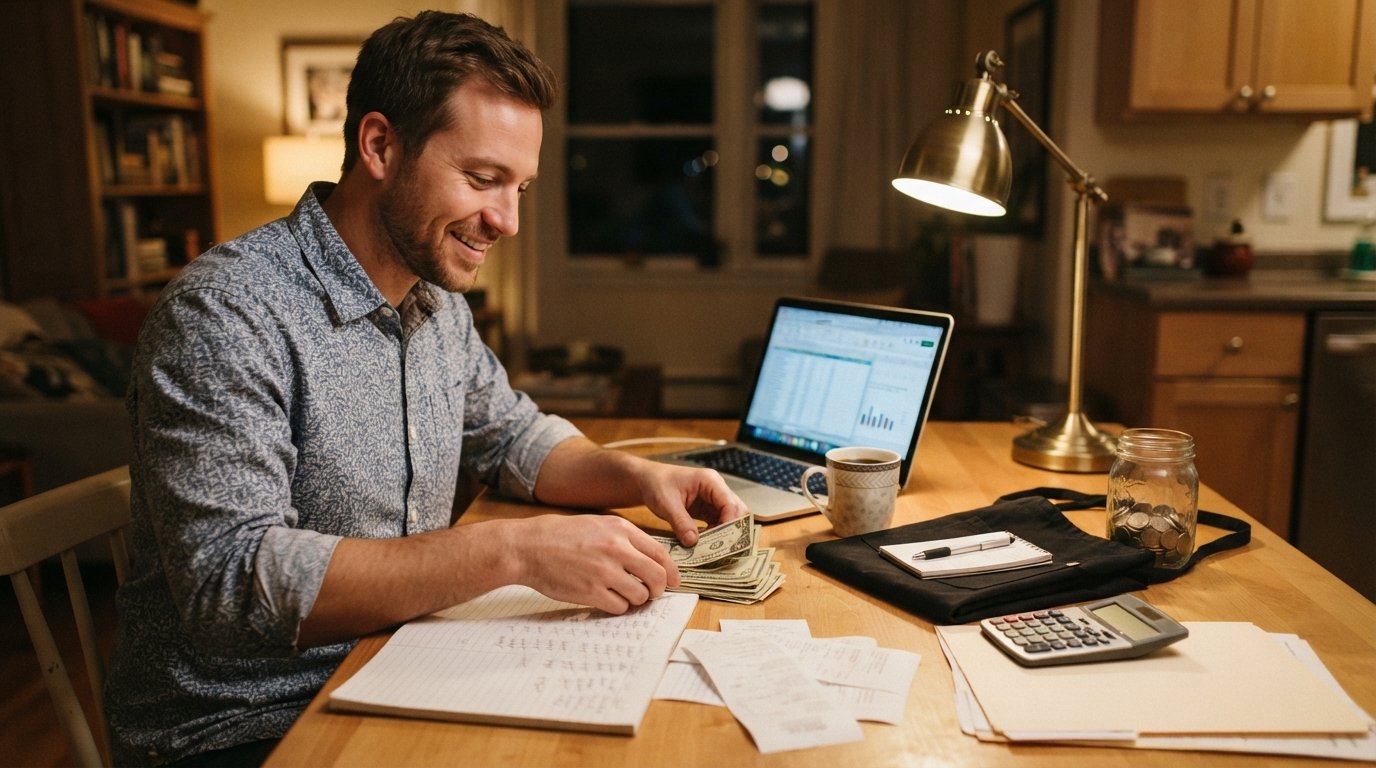
The single most effective step you can take is to deposit your cash and tips into a bank account on a regular schedule. Lenders view bank statements as objective evidence. If you deposit $400 in tips every Friday, that pattern becomes your income story. It does not matter that the money started as cash; what matters is that it moved through a verifiable account. Open a dedicated checking account if you do not already have one, and make deposits at least weekly. Avoid depositing large lump sums once a month, because that can look irregular or even suspicious to an automated underwriting system.
Once you have at least three months of consistent deposits, you can use those statements as proof of income. Some lenders want six months, especially for larger loan amounts. Keep your statements organized and be ready to highlight the deposits that represent your earnings, not transfers from friends or one-time windfalls. If you receive tips in a pooled system, ask your employer for a written summary of your share. Even a simple letter on company letterhead can strengthen your file.
Here are the key documents that can bridge the gap between cash income and loan approval:
- Bank statements: Three to six months showing regular cash and tip deposits.
- Tax returns: Your most recent federal return, especially if you reported tip income.
- Profit-and-loss statement: A self-prepared summary of income and expenses if you are an independent contractor.
- Employer letter: A written statement from your manager confirming your role and average tips.
- Receipts or tip logs: A daily record of cash tips, especially if you have not deposited them yet.
These documents work together. A bank statement shows the money arrived. A tax return shows you reported it. A profit-and-loss statement explains the flow. An employer letter adds a human voice. You do not need every single item for every loan, but the more layers you can provide, the more confident a lender will feel.
Choose the Right Loan Type for Your Income Profile
Not all loans are created equal when your income is cash-based. Short-term loans, including payday loans, cash advances, and installment loans, tend to have more flexible verification requirements. Many online lenders in this space use alternative data, such as bank account transactions, to assess your ability to repay. That makes them a practical starting point for tipped workers who need fast funding for an unexpected bill.
Personal loans from online marketplaces may also work if you can show consistent deposits. These loans are typically unsecured, meaning you do not need collateral, and they come with fixed monthly payments. The interest rate will depend on your credit score, income stability, and the lender's own criteria. If your credit is less than perfect, you can still find options, but expect to pay a higher rate. The key is to borrow only what you can comfortably repay when your income is variable.
Auto loans and mortgages are a different challenge. They usually require tax returns and sometimes a formal profit-and-loss statement prepared by an accountant. If you are aiming for a large loan, plan ahead by reporting your tips accurately for at least two years. That gives you a documented income history that traditional underwriters can accept. For immediate needs, though, a short-term online loan is often the most realistic path. You can explore express cash loans for fast funding to see how a connector platform matches your request with lenders who are comfortable with cash income.
How to Present Your Income on a Loan Application
When you fill out a loan application, you will be asked to state your monthly income. Do not guess. Calculate a realistic average based on your deposits and tip logs. Add up your total earnings over the last three months and divide by three. If your income fluctuates, use the lowest month or a conservative average. Lenders prefer accuracy over optimism, and overstating your income can lead to a denial or a loan you cannot afford.
Be prepared to explain any gaps or unusual deposits. If you took a two-week vacation and your income dropped, say so. If you received a large tip from a holiday party, note that it was a one-time event. Transparency builds trust. Many online applications allow you to upload documents directly, so have your bank statements and tax returns saved as PDFs before you start.
If you are applying through a platform like ExpressCash, the process is designed to be simple. You enter your details, get matched with lenders, and review offers. The platform itself is not a lender, but it connects you with a network of third-party lenders who may consider cash income. You can submit a free request and see what options appear. Just remember that loan availability and terms vary by state and by lender.
Improve Your Approval Odds With These Practical Moves
Beyond documentation, there are several steps you can take to strengthen your application. First, check your credit report for errors. A mistake on your credit file can lower your score and cost you better rates. You are entitled to a free report from each major bureau every year. Dispute anything that is inaccurate. Second, pay down existing debt if you can. A lower debt-to-income ratio makes you a safer borrower in the eyes of any lender.
Third, consider adding a co-signer if your credit history is thin or damaged. A co-signer with strong credit and verifiable income can sometimes tip the scales in your favor. Not all lenders allow co-signers for short-term loans, but some do. Fourth, start with a smaller loan amount. A $500 loan is easier to approve than a $5,000 loan, and successfully repaying it can build a positive track record that helps you qualify for more next time.
Finally, do not apply to multiple lenders all at once. Each application may trigger a hard credit inquiry, which can temporarily lower your score. Instead, use a connector service that matches you with multiple lenders through a single request. That way you can compare offers without damaging your credit repeatedly. For individuals seeking quick access to funds, a service like 4Payday can streamline the process by connecting you with lenders who specialize in short-term options.
Understand the Costs and Borrow Responsibly
Short-term loans and cash advances can carry high interest rates and fees. Before you accept any offer, read the terms carefully. Look at the annual percentage rate (APR), the repayment schedule, and any late fees. A loan that seems easy to get can become expensive if you miss a payment. Only borrow what you are confident you can repay on time. If your income is unpredictable, consider a smaller loan or an installment loan with more flexible repayment terms.
It also helps to have a small emergency fund set aside for future surprises. Even $500 in savings can reduce your reliance on loans. If you receive cash tips, set aside a portion each week into a separate savings account. That habit builds financial resilience and can improve your ability to qualify for better loan terms down the road.
Qualifying for a loan when you are paid in cash or tips is not about hiding your income; it is about proving it. With consistent bank deposits, accurate tax reporting, and the right loan product, you can access the funding you need without a traditional paycheck. Take the time to organize your documents, choose a lender or connector that understands variable income, and borrow only what you can repay. That approach protects your financial future while solving today's urgent need.