How to Pick a Loan Amount You Can Actually Repay
Pick a loan amount you can actually repay by budgeting first. Call (833)-856-0496 for guidance on matching your payment to your income.
By Hannah Adler
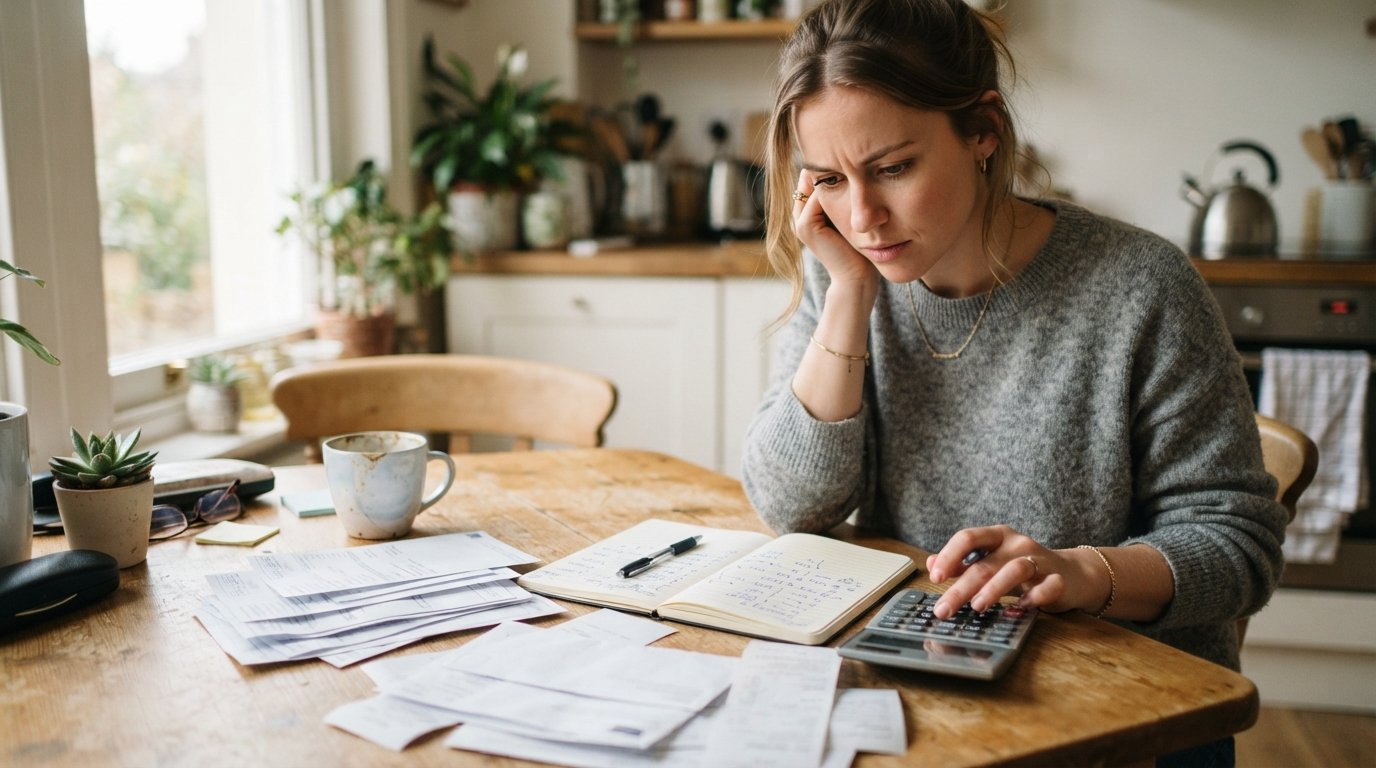
A loan offer can feel like a lifeline when an unexpected bill lands on your kitchen table. But the number a lender approves and the number your bank account can truly support are often two very different figures. The gap between those numbers is where financial stress begins. Learning how to pick a loan amount you can actually repay is not about being overly cautious or missing out on needed funds; it is about protecting your future self from a cycle of payment pressure that can last for months or even years. Whether you are covering a car repair, a medical bill, or a gap in income, the amount you borrow should be anchored to your real budget, not to the maximum a lender is willing to offer.
Start With What You Can Comfortably Pay Each Month
The most reliable method for sizing a loan is to work backwards from your monthly cash flow. Before you look at any offer, sit down with your income and your fixed expenses. Fixed expenses include rent or mortgage, utilities, insurance, groceries, transportation, minimum debt payments, and any child or dependent care costs. Subtract those from your take-home pay, and you have a rough picture of what is left over each month.
That leftover amount is not automatically available for a loan payment. You also need room for savings, irregular expenses like car maintenance or school supplies, and a buffer for the unexpected. A practical rule is to keep your total monthly debt payments, including the new loan, below 36 percent of your gross monthly income. If your existing debts already push you close to that line, a new loan payment will strain your budget quickly.
Once you know your comfortable monthly payment range, you can use a loan calculator or ask potential lenders for payment estimates at different borrowing amounts. This step turns an abstract number into a concrete monthly obligation, which is exactly the perspective you need before signing anything. For example, if you can comfortably set aside $150 per month without touching savings, then your loan amount should be based on what produces a payment near that figure, not on the $2,500 maximum you were approved for.
Why Borrowing the Maximum Can Backfire
Lenders approve borrowers for amounts based on their credit profile, income verification, and internal risk models. That approval is a ceiling, not a recommendation. Borrowing the full amount you qualify for is one of the most common mistakes people make, and it often leads to payment shock when the first bill arrives.
When you borrow more than you need, you pay interest on money that sits in your checking account rather than solving your problem. That extra interest increases the total cost of the loan and reduces the financial breathing room you worked so hard to protect. In some cases, a larger loan also extends the repayment term, which means you stay in debt longer and pay even more over time.
There is also a psychological trap: a large loan balance can create a false sense of security. You might spend the surplus on non-essential items, and then find yourself short when the next emergency appears. The safer approach is to borrow only what the specific expense requires, plus a small cushion if the cost is variable. If you are covering a $900 repair, a $1,000 loan may make sense. A $3,000 loan does not, even if the lender offers it.
If you are exploring short-term options and want to understand how timing affects funding, our guide on whether instant cash loans can be delayed explains what to expect during the application and disbursement process.
Factor in Fees and the Total Repayment Cost
The monthly payment is only one piece of the puzzle. A loan with a low monthly payment but a long term and high fees can cost far more than a loan with a slightly higher payment and a shorter term. To pick a loan amount you can actually repay, you need to look at the total repayment cost, not just the number due each month.
Ask each lender for a full breakdown of fees, including origination fees, application fees, late payment fees, and prepayment penalties if any. Then add up every payment you will make over the life of the loan. This total is the real price of borrowing. Compare that total against the amount you are borrowing to see how much the loan costs you in absolute terms.
Here are the key figures to collect from any loan offer before you decide on an amount:
- The amount financed and the stated interest rate or APR
- All upfront fees deducted from the loan proceeds
- The number of payments and the payment frequency
- The total of all payments over the life of the loan
- Any penalties for late payments or early payoff
With those numbers in hand, you can see whether a smaller loan amount with a shorter term might actually cost less overall than a larger loan with a longer term. Sometimes borrowing $1,200 and repaying it over 12 months is cheaper than borrowing $2,000 and repaying it over 24 months, even if the monthly payment on the larger loan looks more manageable. The goal is to minimize total cost while keeping the payment affordable.
Build the Payment Into Your Budget Before You Accept
Before you accept any loan offer, run a trial month. Take your current budget and insert the proposed loan payment as a fixed expense. Then ask yourself whether you can still cover groceries, transportation, and savings without relying on credit cards or another loan. If the answer is no, the loan amount is too high, regardless of what the lender approved.
This trial period is also a good time to check your calendar for irregular expenses. Do you have a car registration coming up, a holiday season, or a tuition payment? If those costs fall within the repayment period, you need to account for them now. A payment that fits in a quiet month may not fit in a busy one.
Another practical step is to set up automatic payments from an account that holds only your bill-paying money. This separation makes it easier to see whether the payment clears without causing overdrafts. If you find yourself checking the balance nervously before each due date, that is a sign the payment is too large for your comfort level.
Working with a platform that connects you to multiple lenders can make it easier to compare offers and find a payment that fits your budget. Services like CashLoanFunded allow you to submit a request and review options from independent lenders, which gives you more control over the amount and terms you choose. Just remember that the final decision about how much to borrow is yours, not the lender's.
Choose a Repayment Term That Matches Your Cash Flow
The loan amount and the repayment term work together. A shorter term means higher monthly payments but less interest overall. A longer term means lower monthly payments but more total interest and a longer commitment. The right balance depends on how stable your income is and how much room you have in your budget.
If your income is steady and you have a comfortable surplus each month, a shorter term can save you money. If your income fluctuates or you have other financial obligations, a slightly longer term may reduce the risk of missed payments, but you should still aim to pay off the loan as early as possible without penalties. Some lenders allow extra payments or early payoff without fees, which can help you reduce the total cost even on a longer-term loan.
When comparing offers, ask each lender whether there are any restrictions on early repayment. A loan that allows you to pay extra toward the principal gives you flexibility to shorten the term if your financial situation improves. That flexibility can be worth more than a slightly lower interest rate, especially if you expect your income to grow.
Stress-Test Your Decision Against a Worst-Case Month
Even the best budget can be derailed by an unexpected expense. Before you commit to a loan amount, imagine a month where your car breaks down or a medical bill arrives. Would you still be able to make your loan payment without missing other obligations? If the answer is uncertain, reduce the loan amount or increase the repayment term until the payment feels safe even in a difficult month.
This stress test is not about pessimism; it is about realism. Lenders assess risk, and you should too. A loan that fits comfortably in a good month but creates panic in a bad month is not a loan you can actually repay. The goal is a payment that remains manageable across a range of scenarios, not just the best-case one.
One way to build in a safety margin is to borrow slightly less than your maximum comfortable payment allows. If your budget can handle $200 per month, consider a loan amount that produces a payment of $170 to $180. The extra room gives you breathing space for months when other costs run high, and it reduces the chance that you will need to borrow again to cover the first loan.
Finally, review your credit profile and your overall debt load before you apply. A higher credit score can unlock better interest rates, which means you can borrow the same amount for less money. If your credit needs work, focusing on improving it before taking on new debt can save you significantly over time. Responsible borrowing is a skill, and it starts with knowing your limits and respecting them.
Picking a loan amount you can actually repay comes down to three habits: knowing your monthly surplus, ignoring the maximum approval in favor of the minimum need, and testing the payment against real-life scenarios before you sign. When you approach borrowing with that mindset, a loan becomes a tool for solving a problem rather than a source of new ones.