How to Handle a Sudden Car Repair Bill Without a Credit Card
A sudden car repair bill without a credit card is stressful, but you can cover it with payment plans, short-term loans, and smart safety calls.
By Hannah Adler
The check engine light flashes, the brakes grind, or the transmission slips, and suddenly you are staring at a repair estimate that could wipe out your savings. If you do not have a credit card, the pressure feels even heavier. You might be tempted to panic or ignore the problem, but neither approach gets your car back on the road. The good news is that there are practical, realistic ways to cover a sudden car repair bill without a credit card, and many of them start with a simple conversation or a smart funding choice.
This guide walks you through your options, from negotiating with the shop to using a short-term loan, and helps you decide whether to repair now or wait. You will also learn how to build a repair fund so the next surprise does not derail your finances. Let us start with the first call you should make.
Talk to the Shop Before You Panic
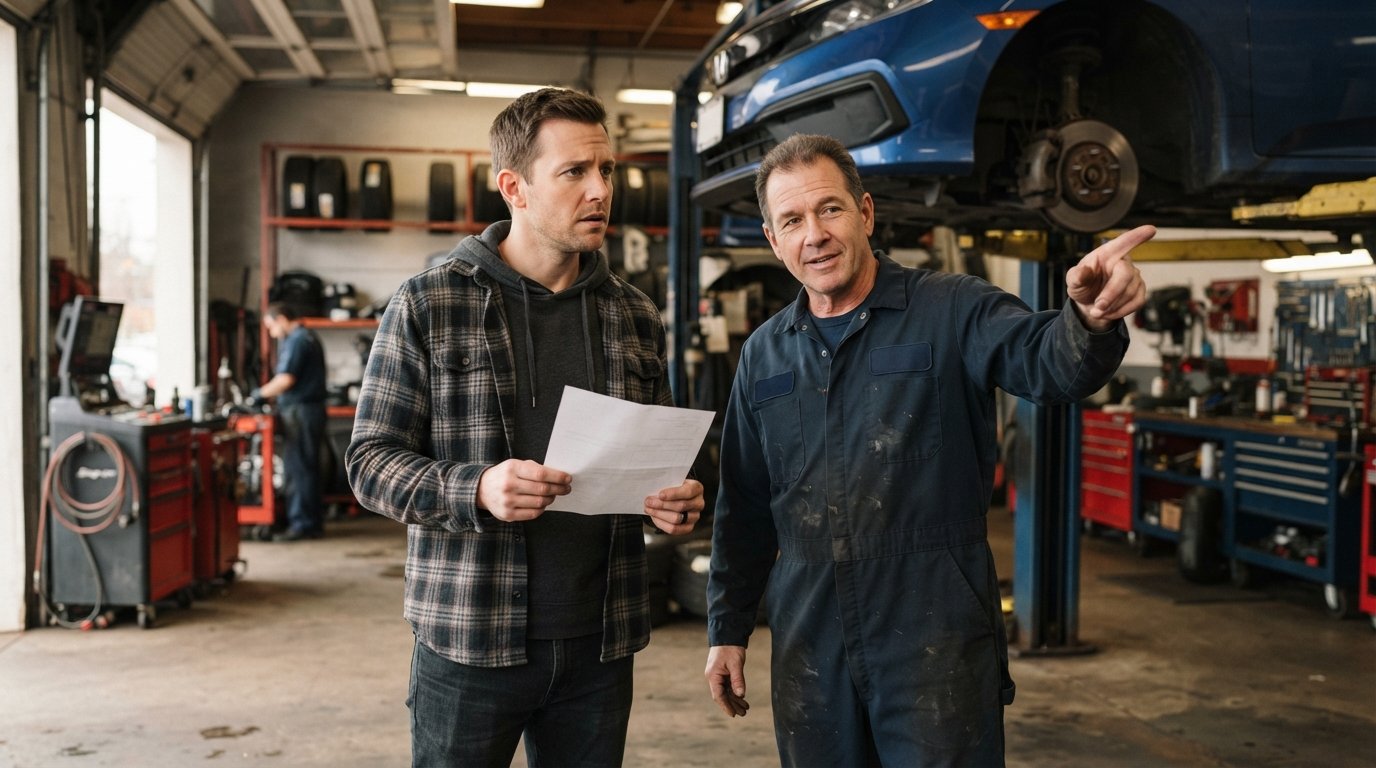
Before you explore loans or dip into savings, have an honest conversation with the repair shop. Many independent mechanics and even some dealership service centers offer payment plans or will let you split the work into stages. The key is to ask early, before the work begins, and to be clear about what you can afford. A good shop would rather work with you than send you away.
Ask specifically about two things: a payment plan and a staged repair. A payment plan might let you pay half now and half in two weeks, sometimes with a small service fee. A staged repair means fixing only the most critical safety items first and postponing less urgent work. For example, if your brakes are metal-on-metal but your air conditioning is broken, you can safety-fix the brakes now and deal with the AC later. This approach reduces the immediate bill and buys you time to gather funds.
Here are a few questions to ask the service advisor:
- Can I pay part of the bill today and the rest on a specific date?
- Which repairs are absolutely necessary for safe driving, and which can wait?
- Do you offer any in-house financing or a layaway-style plan?
- Can you provide a written estimate that separates safety items from cosmetic or comfort items?
If the shop says no to a payment plan, ask if they work with a third-party financing company. Some shops partner with lenders that offer short-term financing, though you should review the terms carefully. Even if they do not, the conversation often reveals flexibility you did not expect. Remember, the goal is to reduce the immediate cash outlay without putting the repair on a credit card.
Consider a Short-Term Loan for the Repair Amount
When you need cash fast and do not have a credit card, a short-term loan can bridge the gap. These loans are designed for emergencies and can be funded as soon as the next business day. However, they are not one-size-fits-all. You need to understand the different types and choose the one that fits your situation and your ability to repay.
There are several short-term loan options to consider. A personal loan from an online lender gives you a lump sum with a fixed repayment schedule, often over several months. An installment loan is similar but may have more flexible terms. A payday loan is a very short-term loan, usually due on your next payday, and can be expensive if rolled over. A cash advance from a service like AdvanceCash connects you with lenders who may offer small, short-term loans. Each option has trade-offs in terms of speed, cost, and repayment terms.
If you are leaning toward a personal loan, our guide on car repair personal loans explains how to apply and what to expect. The process typically involves an online application, a soft credit check, and a decision within minutes. You can borrow the exact amount of your repair bill, which helps you avoid over-borrowing. Just be sure to compare the APR, fees, and repayment terms from multiple lenders before you commit.
Before you apply, gather your documents: proof of income, a government-issued ID, and your repair estimate. Having these ready speeds up the process. Also, check your credit score to see where you stand. Even if your credit is less than perfect, many lenders work with borrowers across the credit spectrum. The key is to borrow only what you need and to have a clear plan to repay on time.
Repair Now or Later: Making the Safety Call
Not all repairs are created equal. Some can wait a few weeks, while others are urgent safety issues. If your car is undriveable, you have little choice but to fix it now. But if the car runs, you need to decide whether to repair immediately or postpone. This decision should be based on safety, not just cost.
Use this simple framework to prioritize repairs:
- Safety-critical: Brakes, steering, tires, suspension, and anything that affects your ability to control the car. Fix these immediately.
- Reliability-critical: Battery, alternator, starter, and cooling system. These can leave you stranded, so address them soon.
- Comfort and convenience: Air conditioning, radio, power windows, and cosmetic damage. These can wait if money is tight.
If the repair is not safety-critical, you might be able to save for a few weeks and pay cash. But do not postpone safety repairs. Driving on bad brakes or bald tires risks your life and the lives of others, and it can lead to more expensive damage down the road. If you are unsure, ask the mechanic to rank the repairs by urgency. A reputable shop will give you an honest assessment.
In some cases, you might also consider whether the car is worth repairing. If the repair cost exceeds the value of the car, it might be time to look for a replacement. But that is a bigger decision, and for now, focus on getting back on the road safely.
Compare Funding Options Quickly When the Car Is Undriveable
If your car is undriveable, you need a solution fast. Waiting for a paycheck or selling items online may not be feasible. In this situation, you need to compare funding options side by side and choose the one that gets you the cash quickly and affordably. Here is a quick comparison of common options when you do not have a credit card.
First, consider a short-term loan from an online connector. These services let you submit one request and get matched with multiple lenders. You can often see offers within minutes and receive funds as soon as the next business day. This speed is crucial when your car is in the shop. Second, check if you have a personal line of credit with your bank or credit union. Even without a credit card, you might have overdraft protection or a small line of credit you can draw on. Third, ask family or friends for a short-term loan. It is not always comfortable, but it can be interest-free and flexible. Finally, look into local assistance programs or charities that help with emergency car repairs. Some community organizations offer grants or low-interest loans for exactly this situation.
When comparing options, look at the total cost, not just the monthly payment. A loan with a low monthly payment but a long term can cost more in interest. Also, check for prepayment penalties and late fees. If you use an online lender, read the terms carefully and make sure you understand the APR. The fastest option is not always the cheapest, but when your car is undriveable, speed matters. Balance both factors.
One more tip: if you have a savings account, even a small one, use it first. You will avoid interest and fees entirely. If you do not have enough, combine savings with a small loan to cover the rest. This reduces the amount you need to borrow and the cost of the loan.
Build a Repair Fund Going Forward
Once the immediate crisis is over, the best way to handle the next repair bill is to have a fund ready. A repair fund is a dedicated savings account for car maintenance and repairs. Even setting aside $20 or $50 per paycheck can add up quickly. The goal is to have enough to cover common repairs, like brakes or a battery, without needing a loan.
Start by estimating your annual car repair costs. A good rule of thumb is to save 1% to 2% of your car's value each year for maintenance and repairs. If your car is worth $10,000, aim to save $100 to $200 per year. That might not cover a major transmission failure, but it will handle smaller issues. Set up an automatic transfer to a separate savings account so you do not accidentally spend the money.
Also, keep up with routine maintenance. Regular oil changes, tire rotations, and brake inspections can prevent costly breakdowns. A $50 oil change can save you a $3,000 engine replacement. If you are not sure what maintenance your car needs, check the owner's manual or ask your mechanic for a schedule. Prevention is the cheapest repair strategy.
Finally, consider a rewards or cash-back program for your everyday spending. Some apps let you round up purchases to the nearest dollar and save the difference. Over time, these small amounts can grow into a decent repair fund. The key is consistency, not the amount.
Handling a sudden car repair bill without a credit card is stressful, but you have more options than you think. Start by talking to the shop about payment plans or staged repairs. If you need cash fast, compare short-term loans and other funding sources carefully. Make safety your top priority when deciding what to fix now. And once the crisis passes, build a repair fund so you are prepared next time. With a clear plan, you can get your car back on the road without relying on credit cards.