How to Cover a Car Insurance Deductible After an Accident
Cover your car insurance deductible after an accident without panic. Call 8338560496 for fast funding options and get back on the road.
By Hannah Adler
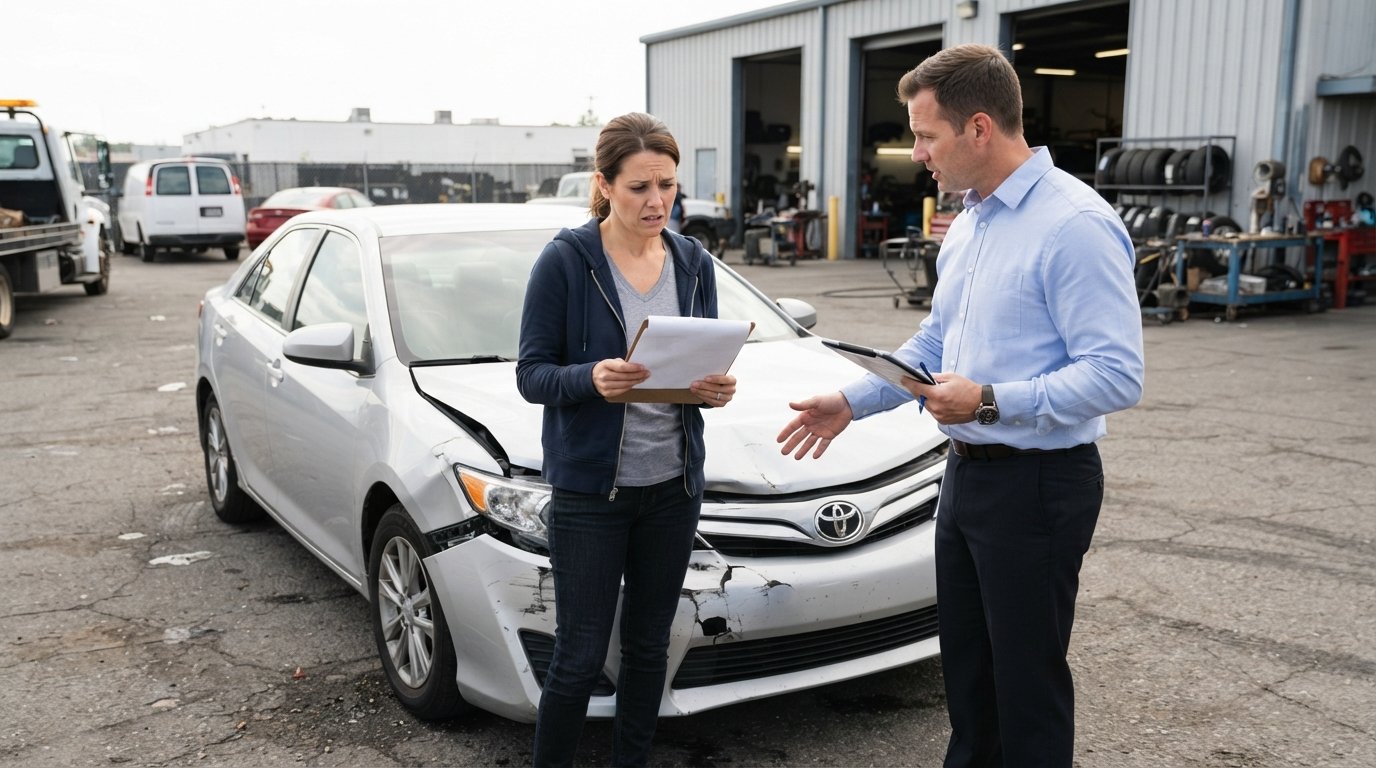
Your hands are still shaking from the crash, and now the insurance adjuster has handed you a number that makes your stomach drop: your deductible. Whether it is $500 or $2,000, that amount is due before your insurer pays a single dollar for repairs. For many drivers, finding that money after an accident feels impossible, especially when the accident already disrupted your work, your schedule, and your peace of mind. The good news is that you have more options than you might think, and understanding them can mean the difference between your car sitting in the shop for weeks and getting back on the road quickly.
This guide walks you through how to cover a car insurance deductible after an accident using practical strategies, from negotiating with repair shops to accessing short-term funding when time is not on your side. You will also learn how fault, state law, and your policy details can shift who ultimately pays that deductible, and what to do if you simply cannot come up with the cash right away.
What Your Deductible Actually Means After a Crash
Your car insurance deductible is the amount you agree to pay out of pocket before your insurer covers the rest of a covered claim. If your deductible is $500 and the repair estimate is $3,500, you pay $500 and your insurer pays $3,000, minus any depreciation or policy limits that apply. This applies to collision coverage and, in many cases, comprehensive coverage, though liability claims work differently because they pay the other driver, not your own vehicle.
The deductible is not a fee your insurer charges you. It is a cost-sharing arrangement built into your policy, and it directly affects your premium. Choosing a higher deductible lowers your monthly payment but leaves you more exposed after an accident. That trade-off becomes painfully clear when you are staring at a repair bill and wondering where the money will come from.
One important nuance: if the other driver is at fault, their liability insurance should cover your repairs, and you generally do not owe your own deductible. However, you may still need to pay your deductible upfront if you file through your own collision coverage while waiting for the at-fault insurer to reimburse you. That reimbursement process can take weeks or months, which is why many drivers look for ways to cover the deductible immediately and recover the money later.
Strategies to Cover Your Deductible Without Borrowing
Before you consider any type of loan or credit, it is worth exploring the resources you already have. Many drivers overlook simple options that can close the gap without adding debt. The key is to act quickly, because repair shops often will not release your vehicle until the deductible portion is settled.
Start by reviewing your emergency savings, even if it is modest. If you have a savings account, a health savings account you can reimburse yourself from, or a flexible spending account, those funds can be used for vehicle repairs in many cases. Next, consider whether you have a rewards credit card with a low or zero introductory APR. Putting the deductible on a card is not ideal, but if you can pay it off within the promotional period, you avoid interest and keep your car in the shop without delay.
Here are several no-debt or low-debt approaches worth evaluating:
- Negotiate with the repair shop: Some shops offer payment plans for the deductible portion, especially if you are a repeat customer or the repair is straightforward.
- Ask about a deductible payment plan through your insurer: A few insurers allow you to pay the deductible in installments, though this is not universal.
- Use a credit card with a 0% introductory APR: This buys you time to pay off the balance without interest, as long as you clear it before the promo ends.
- Tap a flexible spending account or HSA: If your plan allows reimbursement for car repairs related to medical needs, check the rules carefully.
- Sell unused items: A quick online sale of electronics, furniture, or tools can generate several hundred dollars fast.
Each of these options has trade-offs. Negotiating with the shop works best when you have a good relationship or the shop wants your business. Credit cards carry risk if you cannot pay them off quickly. Selling items takes time you may not have. Still, exhausting these possibilities first can save you from taking on high-interest debt.
When Fault Shifts the Deductible to the Other Driver
Fault determination is one of the most misunderstood parts of the claims process. If the other driver caused the accident, their liability coverage should pay for your repairs, including the amount you would normally pay as a deductible. In that scenario, you typically file a third-party claim directly with their insurer, and you owe nothing out of pocket.
However, the process rarely moves as smoothly as it sounds. The other insurer may dispute fault, delay payment, or offer a settlement that does not cover the full repair cost. In the meantime, your car may be undrivable, and you may need to use your own collision coverage to get it fixed. When you do that, your insurer pays the repair shop minus your deductible, and then attempts to recover the deductible from the at-fault insurer through subrogation.
Subrogation can take months. If you cannot wait, you have two choices: pay the deductible yourself and wait for reimbursement, or leave the car unrepaired until the other insurer pays. Many drivers choose to pay upfront and recover later, which means they still need to find the deductible amount temporarily. Understanding your state's fault rules (at-fault, no-fault, or comparative negligence) is essential here, because it determines whether you have a realistic path to reimbursement.
Using Short-Term Funding to Bridge the Gap
When savings, negotiation, and fault-based reimbursement are not enough, short-term funding can provide the bridge you need. This is where a service like ExpressCash becomes relevant. ExpressCash is not a lender; it is a connector that matches your loan request with a network of independent lenders who may offer payday loans, personal loans, installment loans, or lines of credit. The application takes less than five minutes, uses 256-bit SSL encryption, and carries no obligation to accept any offer you receive.
For drivers facing a deductible they cannot cover, this kind of matching service can be a practical option because it consolidates the search for funding into one request. Instead of applying to multiple lenders individually and risking multiple hard credit inquiries, you submit one request and review the offers that come back. Funds may be available as soon as the next business day, which aligns well with the urgency of a repair shop waiting for payment.
It is important to approach short-term borrowing with clear eyes. These products often carry high interest rates and fees, and they are best used for genuine emergencies with a plan to repay quickly. Before you accept any offer, read the terms carefully, confirm the total repayment amount, and make sure the monthly payment fits your budget. If you are exploring options for covering unexpected vehicle costs, resources like this guide on smart ways to cover sudden car repairs can help you compare approaches before you commit.
If you decide to pursue a short-term loan, here is a simple framework to follow:
- Submit one request through a connector platform rather than applying to many lenders separately.
- Compare offers side by side: look at APR, fees, repayment term, and total cost, not just the monthly payment.
- Confirm the repair shop's payment timeline so you know exactly when funds must be available.
- Accept only the offer you can repay comfortably within the stated term.
- Set up automatic payments to avoid late fees and protect your credit.
This process works best when you treat the loan as a short-term bridge, not a long-term solution. The goal is to get your car repaired, get back to work, and retire the debt as quickly as possible.
Creative Alternatives When You Cannot Pay the Deductible
Sometimes the numbers simply do not work, and you need alternatives that do not involve borrowing at all. One option is to ask the repair shop to bill your insurer directly and let you pay the deductible in installments. Some shops agree to this because they want the insurance work, and the deductible is a small portion of the total bill. Another option is to use a mechanic who specializes in insurance claims and understands the reimbursement process, which can give you more flexibility on timing.
You can also explore whether your policy includes deductible waiver or deductible reimbursement coverage. Some insurers offer a deductible waiver if you complete a safe driver course, or if the accident involved a hit-and-run or an uninsured driver. These features are not universal, but they are worth checking before you assume you owe the full amount.
If the repair cost is close to your deductible, it may not make sense to file a claim at all. For example, if your deductible is $1,000 and the repair estimate is $1,200, filing a claim could raise your premium and cost you more over time than paying out of pocket. In that case, you would negotiate directly with the shop, pay the full amount yourself, and avoid the claim entirely. This is a strategic decision that depends on your policy, your driving record, and how much you value keeping your premium low.
Protecting Yourself From Deductible Stress in the Future
Once you have handled the immediate crisis, it is worth taking steps to make sure the next accident does not put you in the same position. The most effective approach is to build a dedicated car repair fund. Even setting aside $50 per month creates a $600 cushion in a year, which covers many common deductibles. Treat this fund as untouchable except for vehicle emergencies.
You can also adjust your deductible strategically. If you currently have a $500 deductible and a strong emergency fund, raising it to $1,000 could lower your premium meaningfully. The reverse is also true: if you know you could not cover a $1,000 deductible, keeping it low is worth the higher monthly cost. Review this trade-off once a year or whenever your financial situation changes.
Finally, understand your policy inside and out before you need it. Know whether you have collision and comprehensive coverage, what your deductible is for each, whether you have rental reimbursement, and how your insurer handles subrogation. That knowledge turns a chaotic post-accident experience into a manageable process where you are making decisions from a position of clarity rather than panic.
Covering a car insurance deductible after an accident is rarely easy, but it is almost always manageable with the right combination of savings, negotiation, fault-based reimbursement, and, when necessary, short-term funding. Start with the resources you already have, explore every angle before borrowing, and if you do take on debt, choose the most affordable option and repay it fast. Your car, your budget, and your credit will all be better for it. 4Payday