How to Build a Debt Repayment Plan for Multiple Short Term Loans
Build a debt repayment plan for multiple short term loans with a clear strategy that ranks balances, matches due dates to paychecks, and cuts interest costs.
By Olivia Bennett
Juggling three or four short term loans at once can feel like sprinting on a treadmill that keeps speeding up. Each due date arrives with its own fee, its own interest charge, and its own quiet threat to your budget. The good news is that you do not need a financial degree to regain control. You need a plan, one that ranks your debts, matches them to your cash flow, and gives you a realistic timeline for becoming debt free. This article walks you through how to build a debt repayment plan for multiple short term loans, step by step, with practical examples you can apply this week.
Start With a Complete Debt Inventory
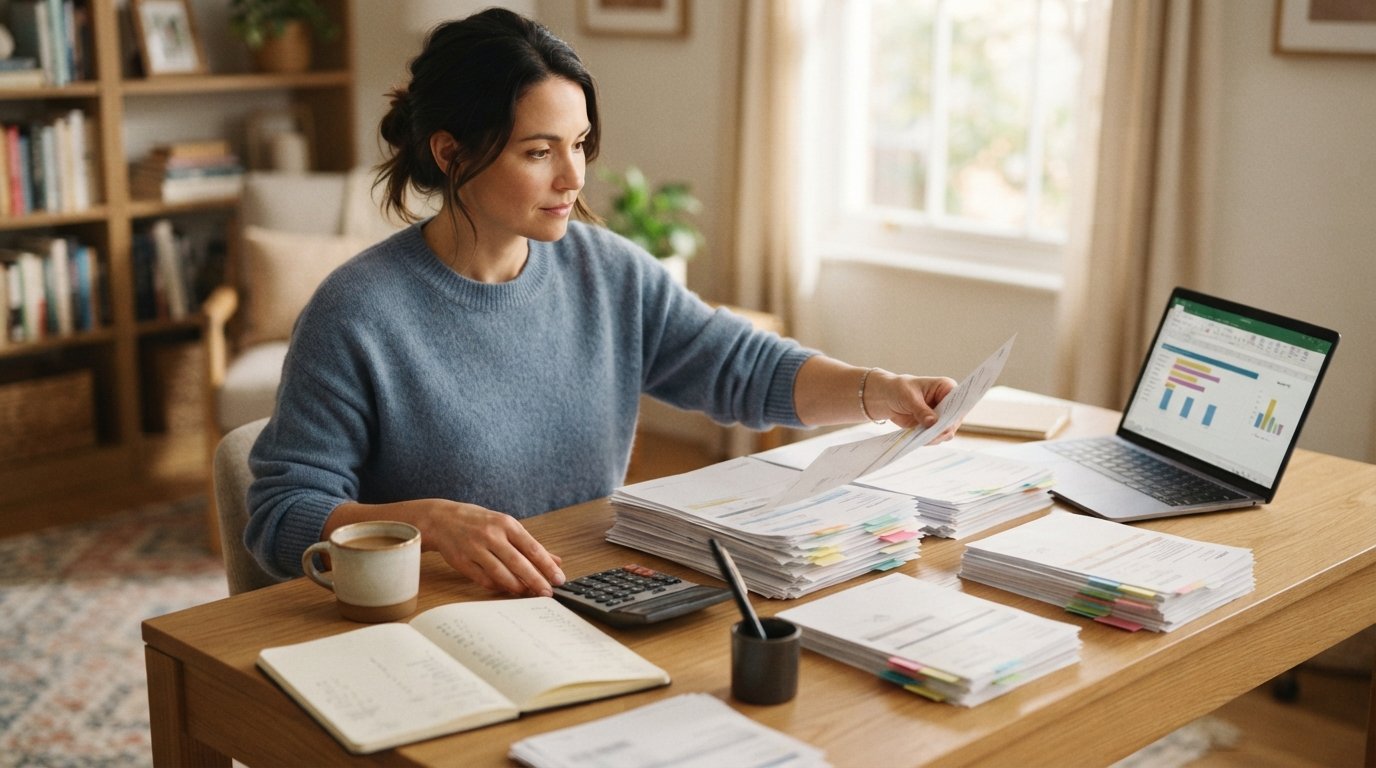
Before you can build any repayment strategy, you need a clear picture of what you owe. Most people carrying several short term loans underestimate both the number of obligations and the total cost of carrying them. Pull together every loan agreement, app notification, or statement you can find and list them in one place.
For each loan, record the lender name, the outstanding balance, the interest rate or finance charge, the minimum payment, and the due date. Do not forget payday loans, cash advances, installment loans, and any buy now, pay later balances that function like short term credit. If you are unsure how repayment mechanics work across different product types, a clear guide to short term funding can help you decode the terms before you start comparing balances.
Once your list is complete, total the balances and add up the minimum payments. That combined monthly figure is your starting point. Many borrowers discover that their minimum payments alone consume 30 to 50 percent of their take home pay, which explains why the debt feels impossible to escape. Seeing the real number is uncomfortable, but it is also the moment your plan becomes possible.
Calculate Your True Monthly Repayment Capacity
Your repayment capacity is not simply what is left after bills. It is what remains after essential expenses, and it must be sustainable for months, not just one pay cycle. Start with your monthly take home income from all sources, then subtract fixed necessities: rent or mortgage, utilities, groceries, transportation, insurance, and minimum payments on any other debts.
What remains is your discretionary income. Some of it should stay untouched for emergencies, because a single unexpected expense can derail even a well designed plan. A common guideline is to dedicate 70 to 80 percent of discretionary income to debt repayment while keeping 20 to 30 percent as a small buffer. If that buffer feels too small, consider temporarily trimming subscriptions, dining out, or other flexible spending until the smallest loan is cleared.
If your discretionary income is zero or negative, do not panic. It means your plan needs to include either an income boost (overtime, a side gig, selling unused items) or a conversation with lenders about hardship options. A repayment plan built on imaginary money will collapse within two months.
Choose a Repayment Strategy That Matches Your Situation
There is no single best method for everyone. The right strategy depends on your balances, your interest rates, and what keeps you motivated. Two proven approaches dominate personal finance for good reason.
- Debt avalanche: Pay minimums on everything, then throw every extra dollar at the loan with the highest interest rate. This saves the most money over time.
- Debt snowball: Pay minimums on everything, then attack the smallest balance first. This delivers quick wins and builds momentum.
- Hybrid approach: Target the highest rate loan that also has a small balance, giving you both savings and a fast victory.
The avalanche method usually wins mathematically, especially with payday loans that carry triple digit annual percentage rates. The snowball method often wins psychologically, because eliminating an entire loan in a few weeks provides tangible proof that progress is happening. If you have ever abandoned a budget because it felt pointless, the snowball may serve you better despite the slightly higher interest cost.
A third option is consolidation, where a new installment loan pays off several smaller debts and leaves you with one monthly payment. This can simplify your life and sometimes lower your rate, but it only works if you stop using the paid off credit lines. Otherwise you simply double your debt. If you are exploring this route, a service that connects consumers with lenders, such as 4Payday, can help you compare short term loan options without committing to any single offer.
Build a Monthly Payment Calendar
Short term loans often come with biweekly or semi monthly due dates, which means a monthly budget alone is not enough. Map every payment to the exact paycheck that will cover it. If two loans land in the same week and your income cannot stretch that far, call one lender and ask to move the due date. Many lenders allow this once or twice per year at no cost.
Your calendar should show, for each pay period, the amount due, the lender, and the source of funds. Then add your extra payment, the amount above the minimum that goes toward your target loan. Writing this down (or entering it in a calendar app with reminders) prevents the late fees that quietly sabotage repayment plans.
Consider aligning due dates with your pay schedule whenever possible. If you are paid on the first and fifteenth, aim to have all loan payments fall within three days after each deposit. This prevents the end of month crunch that forces borrowers to take new loans to cover old ones.
Reduce the Cost of the Debt Itself
A repayment plan is only as strong as the terms underneath it. Before you accept your current rates as fixed, explore every legitimate way to lower them. This is where many borrowers leave hundreds of dollars on the table.
Call each lender and ask about hardship programs, rate reductions, or fee waivers. Ask specifically whether they offer a repayment plan for borrowers in good standing who are trying to catch up. Some lenders will lower your interest rate or extend your term rather than risk default. If you have multiple payday loans, ask whether you qualify for an extended payment plan, which many states require lenders to offer at least once per year.
If your credit has improved since you took out the loans, refinancing may be an option. A new installment loan with a lower rate can replace several high cost debts, but only if the total cost of the new loan is genuinely lower. Always compare the total repayment amount, not just the monthly payment. A longer term with a smaller monthly payment can cost far more in the end.
Automate Payments and Protect Your Progress
Human memory is a terrible payment system. Set up automatic payments or calendar alerts for every due date, and if your lender offers a small discount for autopay, take it. Automation removes the risk of late fees and the temptation to skip a payment when money feels tight.
At the same time, protect your plan from the two most common derailments: new borrowing and irregular income. Pause all new credit applications while you execute your repayment plan, and build a small emergency fund (even $500 helps) so a flat tire does not send you back to a payday lender. If your income varies, base your extra payment on your lowest expected month and treat any surplus as a bonus attack on your target loan.
Track Progress and Adjust Every Month
A repayment plan is a living document. Once a month, sit down for fifteen minutes and update your balances, review what worked, and adjust what did not. Celebrate each loan you eliminate, even the small ones. That emotional fuel matters more than most people admit.
If a month goes badly, do not abandon the plan. Reduce your extra payment to the minimum, keep the habit alive, and resume the attack next month. Consistency beats intensity in debt repayment, because the goal is not one heroic month but a series of ordinary months that add up to freedom.
Building a debt repayment plan for multiple short term loans is ultimately about replacing chaos with structure. You gather the facts, choose a strategy, align payments with your paychecks, lower your costs where you can, and repeat the process until the balances disappear. It is not glamorous, but it works, and it puts you back in control of your financial life.