Emergency Cash for a Funeral or Burial Expense
Facing funeral costs? See typical burial and cremation prices, payment plans funeral homes offer, and how a short term loan can bridge the gap fast.
By Sophia Miller
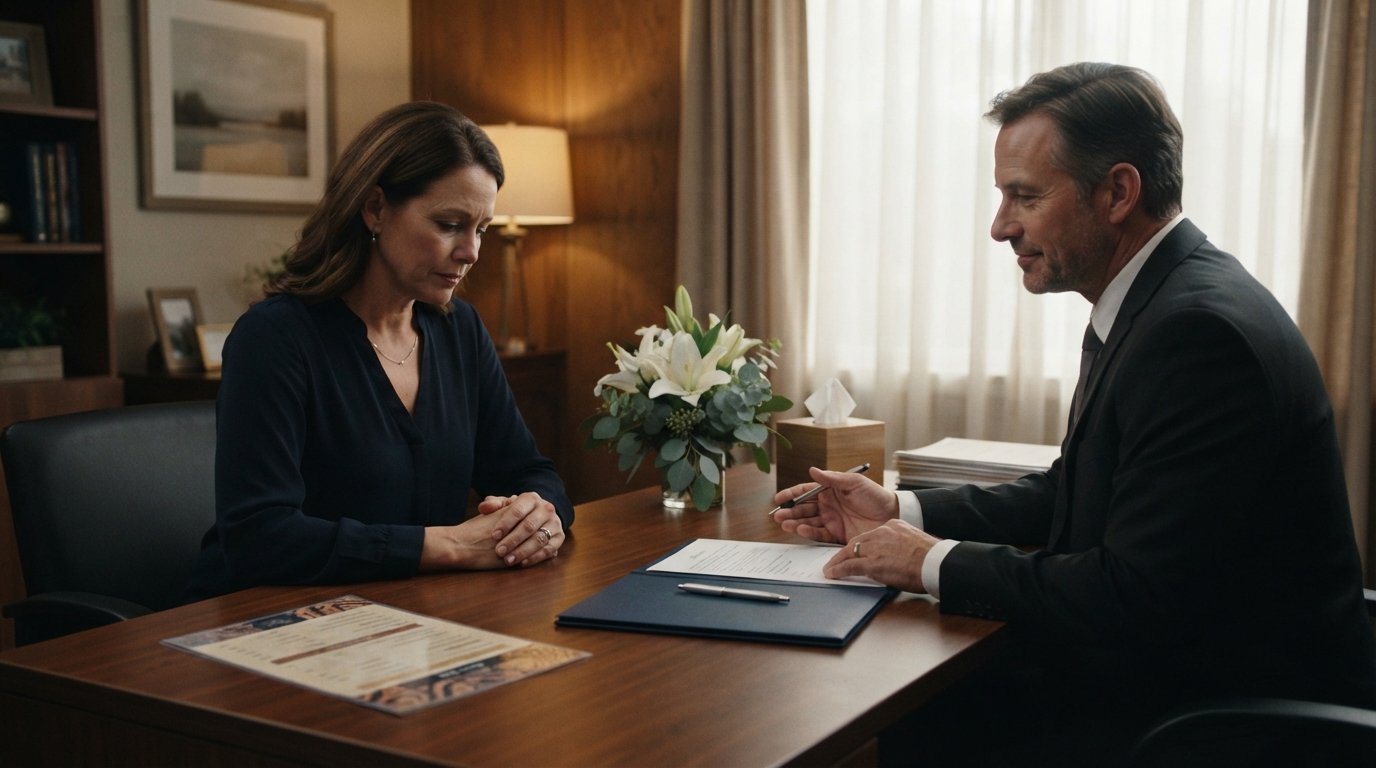
The call comes at 3 a.m., and by sunrise you are sitting in a funeral director's office being handed a laminated price list. Nothing prepares you for the arithmetic of grief: a simple burial plot, a casket, a service, a headstone, and suddenly you are staring at a five-figure number while still processing the loss. Funeral homes generally require payment before services are rendered, and most families do not keep that kind of money in a checking account. If you are searching for emergency cash for a funeral or burial expense, you are not alone, and you are not without options. This guide walks through what funeral costs actually look like, which payment arrangements funeral homes may offer directly, how to tap benefits and assistance programs first, and how a short term or personal loan through a matching service can bridge the gap when the math does not work any other way.
What Funeral and Burial Costs Actually Look Like
The first step toward solving a funding gap is knowing its size. According to long-running industry surveys from the National Funeral Directors Association, the median cost of a traditional funeral with viewing and burial has hovered near $8,000 in recent years, and that figure excludes the cemetery plot, grave marker, and vault, which can add several thousand dollars more. A funeral with cremation runs lower on average, often in the $5,000 to $7,000 range, but direct cremation (no service, no viewing) can cost well under $2,000 in many markets. The spread is enormous, which is why getting an itemized quote before signing anything matters so much.
Geography and provider type move the numbers significantly. A full-service funeral in a major metro area can easily exceed $12,000, while a small-town provider or a nonprofit funeral home may charge half that. Caskets alone range from a few hundred dollars for a simple wood model to $10,000 or more for premium styles, and many families do not realize they can purchase a casket from a third-party retailer and have it shipped to the funeral home. The Federal Trade Commission's Funeral Rule requires funeral providers to give you an itemized general price list, so ask for one and compare line items rather than accepting a package price.
Here is a rough breakdown of the major expense categories families typically face:
- Professional services: transportation of the deceased, embalming, preparation, and staff coordination, often $2,000 to $4,000.
- Merchandise: casket or urn, vault, and marker, ranging from several hundred to over $10,000.
- Facilities and ceremony: viewing, funeral service, and equipment charges, commonly $1,000 to $3,000.
- Cemetery costs: plot, opening and closing the grave, and perpetual care, frequently $1,500 to $5,000 or more.
- Extras: obituary notices, flowers, catering, and clergy honoraria, which can quietly add $500 to $2,000.
Add those ranges together and it is easy to see why a family with modest savings suddenly needs emergency cash for a funeral or burial expense. The good news is that you do not have to pay the first quote you receive, and you do not have to solve the entire gap with borrowed money. A combination of negotiation, benefits, assistance, and a carefully chosen funding source usually closes the distance.
Payment Arrangements Funeral Homes May Offer Directly
Before you borrow anything, talk to the funeral director about the timeline. Many families assume the full balance is due at the time of arrangements, but that is not always the case. Funeral homes routinely work with families who are waiting on life insurance proceeds, and some offer internal installment plans, typically over three to twelve months, sometimes with modest interest or a service fee. Ask directly: "What is your payment schedule, and do you offer in-house financing?" The answer varies by provider and by state, but the question costs nothing and can buy you breathing room.
You can also reduce the bill itself. Choosing direct cremation followed by a memorial service at a later date, renting a casket for viewing instead of purchasing one, providing your own urn, and limiting visitation hours are all legitimate ways to cut costs without sacrificing dignity. Some funeral homes will match or beat a competitor's written quote, and nonprofits and cooperative funeral societies sometimes serve members at cost. If the deceased lived in another state, compare prices near you versus near the burial site, since transporting remains is often cheaper than a high-cost funeral in an expensive market.
One caution: avoid signing a financing agreement on the spot without reading the terms. Some funeral home payment plans carry high effective interest rates, and a few include clauses that assign your life insurance proceeds directly to the provider. If the policy will pay out within a few weeks, a short bridge may be all you need, and a small loan can be cheaper than a long in-house plan. The key is to compare the total cost of each path rather than just the monthly payment.
Tap Benefits, Insurance, and Assistance Before Borrowing
Emergency cash does not always mean a loan. Several sources of money exist specifically for funeral expenses, and you should exhaust the free ones first. Life insurance is the most common: a traditional policy pays a death benefit to the named beneficiary, usually within two to eight weeks after a claim is filed. If you need funds faster, ask the insurer about an accelerated death benefit or an assignment, where the funeral home or a lender advances part of the policy proceeds for a fee. Assignment is not free, but it can be faster than waiting for the full payout.
Employer benefits are frequently overlooked. Many companies offer a small life insurance policy as part of a benefits package, and some provide funeral leave, final paycheck processing, or an employee assistance fund for survivors. Contact the deceased's HR department and ask specifically about life insurance, retirement account beneficiary designations, and any burial assistance the company offers. Unions, fraternal organizations, veterans' groups, and churches often maintain burial funds as well, and veterans may qualify for a burial allowance from the Department of Veterans Affairs.
Public and community assistance can fill smaller gaps. County and state programs sometimes provide burial assistance for low-income families, typically paying a capped amount directly to the funeral home. Social Security pays a one-time lump-sum death payment of $255 to eligible survivors, and the deceased's final Social Security check may be recoverable in some circumstances. Crowdfunding through a platform like GoFundMe has become a mainstream way to raise money for funeral costs, and community groups, religious congregations, and mutual aid networks frequently step in when a family is in need. If you want a broader overview of fast funding routes for urgent situations, our guide on getting emergency cash fast covers the landscape beyond funeral-specific options.
Stack these sources before you borrow. Even a partial benefit reduces the loan amount you need, and every dollar you do not finance is a dollar plus interest you keep. Only after you have confirmed what insurance, employers, and assistance programs will cover should you calculate the remaining shortfall.
How a Short Term or Personal Loan Bridges the Gap
When the gap remains and the service is days away, a short term or personal loan can serve as a bridge until insurance proceeds, employer benefits, or estate funds arrive. This is a classic timing problem rather than a long-term debt problem: the money exists, or will exist, but it is not available at the moment the funeral home needs payment. A loan converts an impossible deadline into a manageable schedule of payments, and for many families that difference is what allows them to proceed with the service they want.
The fastest route is often an online matching service rather than a single bank. Platforms like CashLoanFunded connect borrowers with a network of third-party lenders, letting you submit one request and compare offers from multiple lenders, including options for people with less-than-perfect credit. ExpressCash works the same way: it is a connection service, not a direct lender, and it matches your request with independent lenders who make their own credit decisions and set their own terms. The process is designed to take just a few minutes online, with 256-bit SSL encryption protecting your information, and there is no obligation to accept any offer you receive. You can review the loan options available through the network to see whether a payday loan, installment loan, personal loan, or line of credit fits your situation.
Here is how the process typically works when you need emergency cash for a funeral or burial expense:
- Confirm your shortfall. Subtract confirmed benefits and assistance from the funeral home's itemized total so you borrow only what you need.
- Submit a short online request. Enter basic details about yourself, your income, and the amount you need; the form usually takes under five minutes.
- Compare lender offers. Review the APR, fees, repayment schedule, and total cost of each offer rather than focusing on the monthly payment alone.
- Accept only what fits. Choose the offer with the lowest total cost that you can comfortably repay, and decline the rest with no penalty.
- Receive funds and pay the funeral home. Funding timelines vary by lender, and some can deposit funds as soon as the next business day after approval.
Treat this as bridge financing, not a permanent solution. Pay off the loan as soon as insurance or estate funds arrive, and avoid rolling it over or extending it, since rollover fees can quickly outstrip the original amount borrowed. If your credit is weak, expect higher rates, and compare at least a few offers before committing. Borrowing a modest amount for a short period is far safer than financing the entire funeral on a high-cost product you cannot repay.
Borrowing Wisely When Grief Is Running the Clock
Grief compresses time. Decisions that would normally take a week get made in an afternoon, and lenders know that urgency sells. The single best protection is a written budget: the funeral home's itemized quote on one side, confirmed benefits on the other, and the difference written down before you apply anywhere. With that number in hand, you can evaluate offers calmly, decline anything with fees you do not understand, and keep the loan as small and short as possible. Remember that loan availability and terms vary by state and by lender, and that ExpressCash does not guarantee approval or set rates; those decisions belong to the independent lenders in the network.
Also give yourself permission to simplify. A smaller service with a meaningful gathering later is not a lesser goodbye, and many families find that reducing the financial strain actually helps them grieve. If you do borrow, put the repayment date on a calendar, tell a family member so you have accountability, and contact the lender immediately if a payment is at risk. Lenders are often more flexible before a payment is missed than after.
Emergency cash for a funeral or burial expense is ultimately about buying time and dignity during one of life's hardest weeks. Start with the free money (insurance, employer benefits, veterans' benefits, community assistance), negotiate the funeral bill, and only then consider a short term or personal loan through a matching service to cover the remaining gap. Used as a bridge and repaid promptly, that loan can let you focus on honoring someone you loved instead of on a payment deadline.