Budgeting for a Loan Payment When Income Is Unpredictable
Budgeting for a loan payment when income is unpredictable starts with a buffer built on your lowest month and a due date that follows your strongest pay days.
By Hannah Adler
A freelancer finishes a strong month and feels confident about the upcoming loan payment. Two weeks later, a major client delays an invoice, a gig gets canceled, and the same payment suddenly feels impossible. This is the reality for millions of gig workers, commission earners, seasonal employees, and self-employed professionals across the United States. When your income arrives in unpredictable waves, a fixed loan payment can feel like a fixed weight around your ankle. The good news is that you do not need a perfectly stable paycheck to stay current on a loan. You need a system built for variability, one that plans for the slow weeks instead of assuming every month will be strong. This guide walks through practical, field-tested strategies for budgeting for a loan payment when income is unpredictable, from setting a buffer based on your worst month to choosing a due date that follows your best paydays. The goal is not just to avoid missed payments, but to protect your credit, your peace of mind, and your financial flexibility when the next slow stretch arrives.
Why Traditional Budgeting Fails Variable-Income Earners
Standard budgeting advice assumes a predictable paycheck. It tells you to allocate a fixed percentage of your monthly income to housing, food, savings, and debt. That model works beautifully for salaried employees who see the same number in their bank account every other Friday. For gig workers and commission earners, it falls apart quickly. If you budget based on your best month and then earn half that amount the next month, your entire plan collapses. If you budget based on your worst month, you may feel unnecessarily restricted during strong months and fail to take advantage of the surplus.
The deeper problem is timing. Even when your annual income is solid, the money may not arrive when the loan payment is due. A rideshare driver might have a fantastic week right after the payment date and a terrible week right before it. A graphic designer might receive a large project payment in the middle of the month but nothing at the start. Traditional budgets track monthly totals, but they ignore the rhythm of when cash actually lands in your account. That timing mismatch is the single biggest reason variable-income earners miss payments even when they are earning enough overall.
A better approach treats your loan payment as a fixed obligation with a flexible funding plan. Rather than asking, "How much can I afford this month?" you ask, "How do I make sure this payment is covered no matter what this month brings?" That shift in perspective is the foundation of every strategy that follows.
Set Your Payment Buffer Based on Your Lowest-Earning Month
The first and most important step is to stop using your average income as the basis for your loan payment plan. Averages are misleading when your income swings widely. If you earn $6,000 in a strong month and $2,000 in a slow month, your average is $4,000, but you will never actually experience a $4,000 month. You will experience $6,000 months and $2,000 months, and the $2,000 months are the ones that threaten your payment.
Instead, identify your lowest-earning month over the past twelve months. This is your floor, the amount you can reasonably expect to earn even when things go wrong. Build your essential budget around that floor, not around your average or your best month. Your loan payment, housing, utilities, food, and transportation should all fit within that floor amount. If they do not, you have a structural problem that no budgeting trick can solve, and you may need to renegotiate the loan term, reduce expenses, or increase your income floor before the next payment cycle.
Once your essentials fit within your floor, create a payment buffer. The buffer is a small amount set aside specifically to cover the loan payment during months when your income dips below the floor. A common approach is to set aside enough to cover one full loan payment plus a small cushion for fees or timing issues. For example, if your loan payment is $250, aim to keep $300 in a dedicated buffer account at all times. During strong months, you top it up. During slow months, you draw from it without guilt. The buffer is not savings for a vacation or an emergency fund for car repairs; it is a dedicated repayment reserve that exists solely to keep your loan current. Treating it as untouchable for other purposes is what makes the system work.
Building the buffer takes time, especially if you are starting from zero. Begin with whatever you can spare during strong weeks, even $20 or $50 at a time. The goal is not to build it overnight but to reach a point where one slow month no longer threatens your loan status. Many borrowers find that a $500 to $1,000 buffer provides meaningful breathing room, but even a partial buffer reduces stress and the risk of a missed payment.
Choose a Due Date That Follows Your Strongest Pay Days
The due date on your loan is not always fixed in stone. Many lenders allow you to request a different payment date, especially early in the loan term or when you have a consistent history of on-time payments. For variable-income earners, aligning the due date with your strongest and most reliable pay days is one of the highest-impact changes you can make.
Start by tracking your income for two to three months. Identify the days or weeks when money reliably arrives. A gig worker might receive weekly payouts from a platform on Tuesdays. A freelancer might receive client payments at the end of each month. A seasonal employee might have predictable paydays during the busy season. Once you know when money lands, contact your lender and ask whether the due date can be moved to a few days after your strongest pay day. This gives you a cushion between the money arriving and the payment leaving, reducing the risk that a delayed deposit causes a missed payment.
If your income is truly irregular with no predictable pay days, choose a due date that follows the period when you historically have the most cash on hand. For many people, this is shortly after the first of the month, when rent and other major bills have already been paid and the remaining balance is clearer. For others, it is mid-month after a major client payment. The key is to avoid due dates that fall during your historically slowest weeks. A payment due on the 28th of the month is dangerous if your income typically dries up after the 20th.
When you contact your lender about a due-date change, be specific and polite. Explain that your income is variable and that a different date would help you pay more consistently. Many lenders are willing to accommodate the request because on-time payments benefit both parties. If the first representative says no, ask whether there is a formal process for requesting a due-date change or whether a supervisor can review the request. Persistence often pays off.
Track Irregular Income to Avoid Missed Payments
You cannot manage what you do not measure. For variable-income earners, tracking income is not about creating a perfect spreadsheet; it is about understanding your own patterns well enough to predict when cash will be tight. A simple tracking system is more valuable than an elaborate one you abandon after two weeks.
Start with a basic record of every payment you receive, including the date, the amount, and the source. A notebook, a spreadsheet, or a free budgeting app all work. After two to three months, review the data and look for patterns. Which weeks are consistently strong? Which weeks are consistently weak? Are there months when a particular client or platform reliably pays? Are there seasonal patterns, such as slower summers for rideshare drivers or busier winters for retail workers?
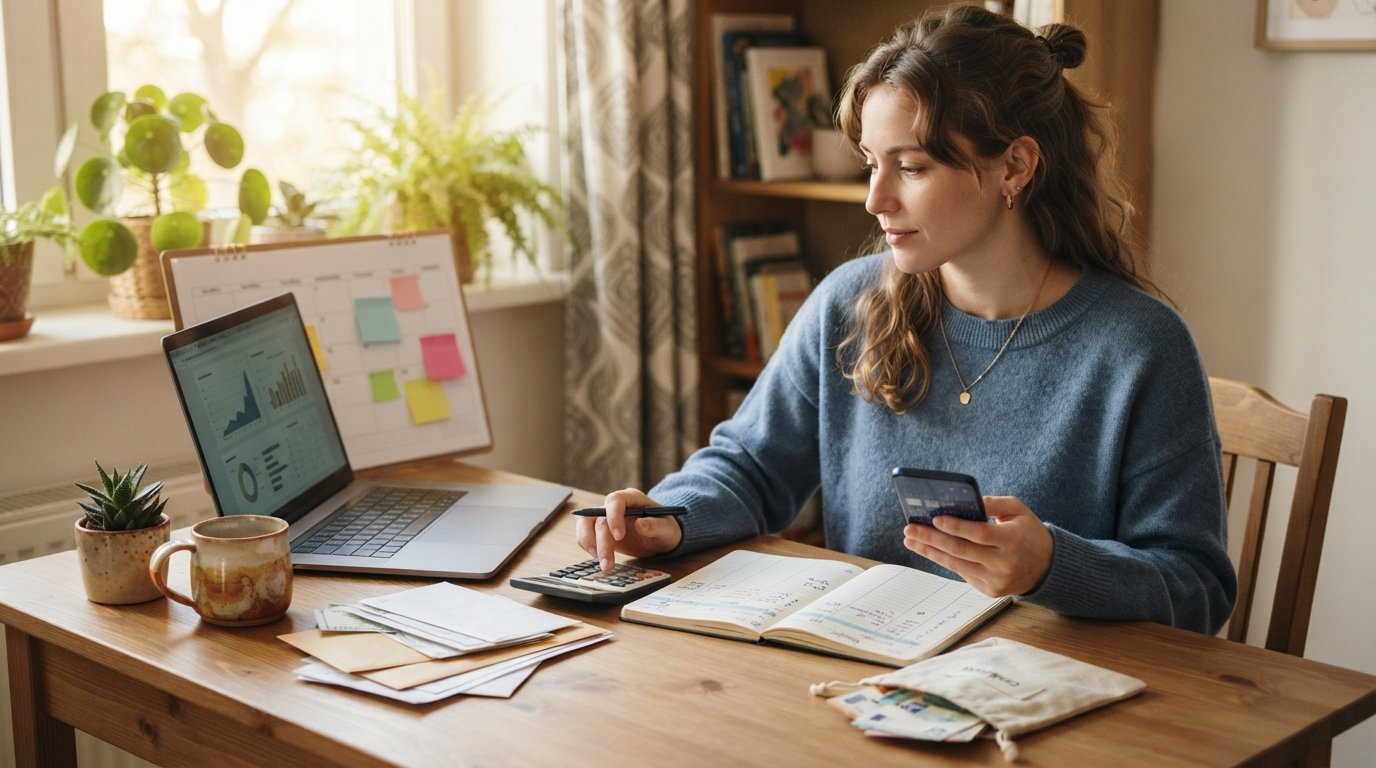
Once you understand your patterns, you can build a simple cash-flow calendar. Mark your loan due date on the calendar, then mark the days when you expect money to arrive. If the due date falls before your expected income, you know in advance that you need to draw from your buffer or adjust your spending. This early warning system is far more effective than checking your balance the day before the payment is due and hoping for the best.
A cash-flow calendar also helps you plan for irregular expenses that compete with your loan payment. Car repairs, medical bills, and annual insurance premiums do not arrive on a predictable schedule, but they are predictable in the sense that they will happen eventually. Building a small reserve for these expenses prevents them from consuming the money you set aside for your loan. If you do miss a payment despite your best efforts, understanding the consequences is essential; our guide on what happens when you miss a fast cash loan payment explains the timeline, fees, and credit impacts so you can respond quickly.
Build a Small Reserve to Cover One Payment
The single most effective safeguard against missed payments is a dedicated reserve that covers at least one full loan payment. This reserve is different from a general emergency fund. An emergency fund exists to handle unexpected expenses like a medical bill or a car breakdown. A payment reserve exists specifically to ensure your loan stays current when income dips. Keeping these two purposes separate prevents the common mistake of raiding the loan reserve for other emergencies and then missing a payment.
Building the reserve requires discipline during strong months. When a large payment arrives, immediately transfer a portion to the reserve before you spend it on anything else. Treat the transfer as a non-negotiable bill, just like rent. Even small transfers add up over time. If you set aside $50 from every strong week, you will have $600 after three months, enough to cover several payments on a typical short-term loan.
The reserve also gives you negotiating power. If you ever need to ask your lender for a due-date change, a short extension, or a modified payment plan, having a reserve demonstrates that you are serious about repayment and simply need a temporary adjustment. Lenders are more willing to work with borrowers who have shown consistent effort than with borrowers who are already behind. For borrowers exploring short-term options, platforms that connect consumers with multiple lenders can be useful; services like StartPaydayLoan help U.S. consumers submit a single request and get matched with third-party lenders, which can make it easier to compare terms before committing to a payment schedule.
Keep the reserve in a separate account from your everyday checking account. A separate account reduces the temptation to spend it on impulse purchases and makes it easier to see exactly how much protection you have. Label the account clearly, such as "Loan Payment Reserve," so its purpose is always visible. Review the balance monthly and top it up whenever it falls below your target.
When to Ask a Lender About Due-Date Changes
Many borrowers wait until they are already behind to contact their lender. That is the worst possible time. Lenders are far more willing to accommodate requests made in advance, before a payment is missed, than to negotiate after a delinquency has been reported. If you see a slow stretch coming, contact your lender early.
Ask about a due-date change when you notice a persistent mismatch between your income timing and your payment date. If your payment is due on the 15th but your main client consistently pays on the 20th, a due-date change to the 22nd or 25th eliminates the mismatch permanently. Ask about a one-time extension when you face an unusual but temporary disruption, such as a hospital stay or a natural disaster that delays your income. Ask about a modified payment plan when your income has dropped for an extended period and the original payment amount is no longer sustainable. In each case, being proactive and specific increases your chances of a positive response.
When you contact your lender, have your income records ready. Explain the pattern you have observed and the specific change you are requesting. For example: "My income arrives primarily in the last week of the month, but my payment is due on the 10th. Could we move the due date to the 28th so I can pay consistently?" This kind of specific, evidence-based request is far more persuasive than a vague plea for help. If the lender agrees, get the change confirmed in writing, whether by email or through your online account, so there is no confusion later.
Putting It All Together: A Monthly Routine for Variable Income
Budgeting for a loan payment when income is unpredictable is not a one-time task; it is a monthly routine. The routine does not need to be complicated, but it does need to be consistent. A simple four-step process, repeated every month, keeps your payment on track regardless of how the month unfolds.
- Review your cash-flow calendar. At the start of each month, mark the loan due date and the days you expect income to arrive. Identify any gaps between incoming cash and the payment date.
- Check your reserve balance. Confirm that your payment reserve covers at least one full payment. If it does not, prioritize topping it up during the first strong income day of the month.
- Transfer to the reserve during strong weeks. When a large payment arrives, move a portion to the reserve before spending on anything else. Even a small transfer maintains the habit.
- Pay early when possible. If cash is available before the due date, pay early rather than waiting. Early payments reduce the risk of a last-minute problem and often simplify your cash-flow planning.
This routine takes less than thirty minutes per month, but it provides a level of control that a traditional budget cannot match. It acknowledges that your income is variable and builds flexibility into the system rather than pretending the variability does not exist. Over time, the routine becomes automatic, and the stress of wondering whether the payment will clear fades.
Variable income does not have to mean variable loan status. With a buffer based on your lowest month, a due date aligned with your strongest pay days, a simple tracking system, and a dedicated reserve, you can keep your loan current even when the weeks are slow. The key is to plan for the dips before they arrive, rather than reacting after a payment is missed. Start with one step this month, whether it is tracking your income or calling your lender about a due-date change, and build from there. Your future self, facing a slow week with a payment already covered, will thank you.